Navigating the Financial Maze of Self-Employment: Key Strategies for Success
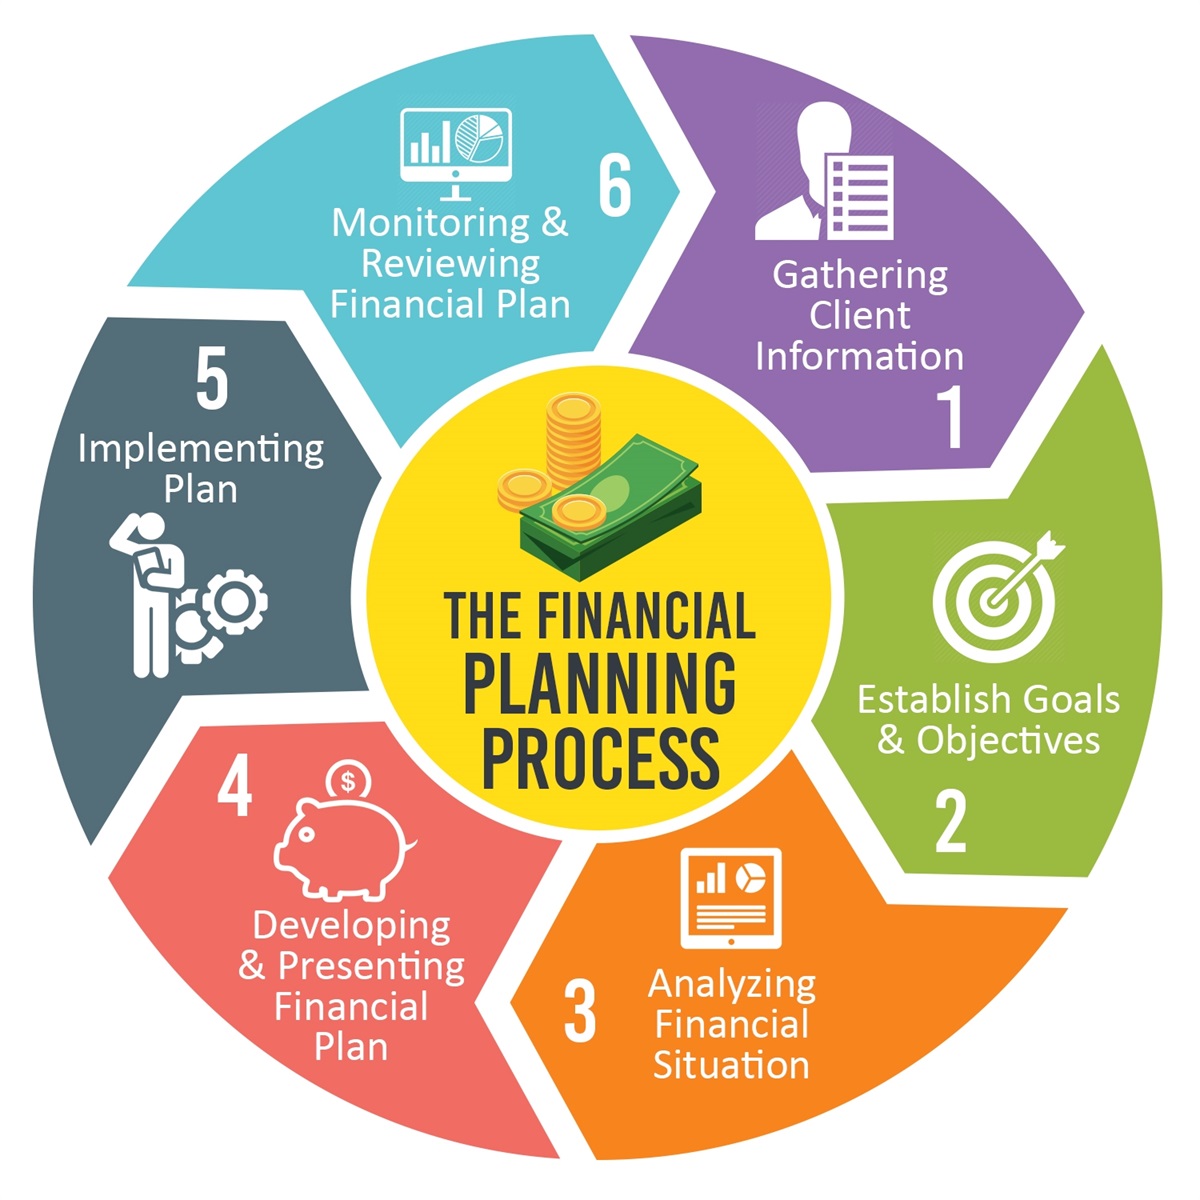
Self-employment income can be a rewarding venture for many individuals, offering the flexibility and autonomy that traditional employment may not provide. However, navigating the world of self-employment comes with its own set of challenges, particularly when it comes to managing your finances effectively. In this article, we will explore key considerations and strategies for handling self-employment income responsibly.
First and foremost, it’s crucial to understand how self-employment income differs from regular employment income. When you are self-employed, you are responsible for paying both the employer and employee portion of payroll taxes, including Social Security and Medicare taxes. This means that you will need to set aside a portion of your income to cover these tax obligations. It’s essential to stay organized and keep accurate records of your earnings and expenses throughout the year to ensure that you are prepared come tax time.
One common pitfall for those new to self-employment is irregular income streams. Unlike a salaried job where you receive a consistent paycheck every month, self-employed individuals often experience fluctuations in their earnings. To mitigate this challenge, consider creating a detailed budget that accounts for both your fixed expenses (such as rent or mortgage payments) and variable expenses (such as utilities or groceries). By planning ahead and setting aside funds during high-income months, you can better weather periods of lower earnings.
Another important aspect of managing self-employment income is setting aside savings for emergencies and retirement. Without access to employer-sponsored benefits like 401(k) plans or health insurance, self-employed individuals must take proactive steps to secure their financial future. Consider opening a retirement account such as a SEP IRA or Solo 401(k), which offer tax advantages while helping you save for retirement.
Health insurance is another crucial consideration for those who are self-employed. Without access to an employer-sponsored plan, finding affordable health coverage can be challenging. Explore options through private insurers or healthcare marketplaces to find a plan that fits your needs and budget. Keep in mind that premiums paid for health insurance may be deductible from your taxable income as a self-employed individual.
Managing cash flow is key when it comes to successfully navigating self-employment income. Set up separate business accounts to track incoming revenue and outgoing expenses related to your work activities. This separation not only simplifies accounting but also helps demonstrate the financial legitimacy of your business in case of an audit.
When setting rates or pricing for your products/services as a self-employed individual, make sure they reflect not only your costs but also factor in profit margins necessary for sustaining growth and weathering economic downturns.
Lastly, don’t forget about quarterly estimated tax payments if applicable based on your level of earnings each quarter – failing to do so could result in penalties at tax time.
In conclusion, managing self-employment income requires discipline, organization,and foresight.Dedicate time regularlyto reviewyourfinancialsituation,and adjustyourstrategyas neededtoavoidcostly mistakesandincreaseyour long-term financialsecurityasaself-employedindividual.Withthe rightapproachandplanning,self-employmentcanbea financiallyrewardingendeavorthatprovidesyouwithbothautonomyandstabilityincomemanagement.