Boost Your Income to Lower Your Debt-to-Income Ratio and Secure Better Loan Terms
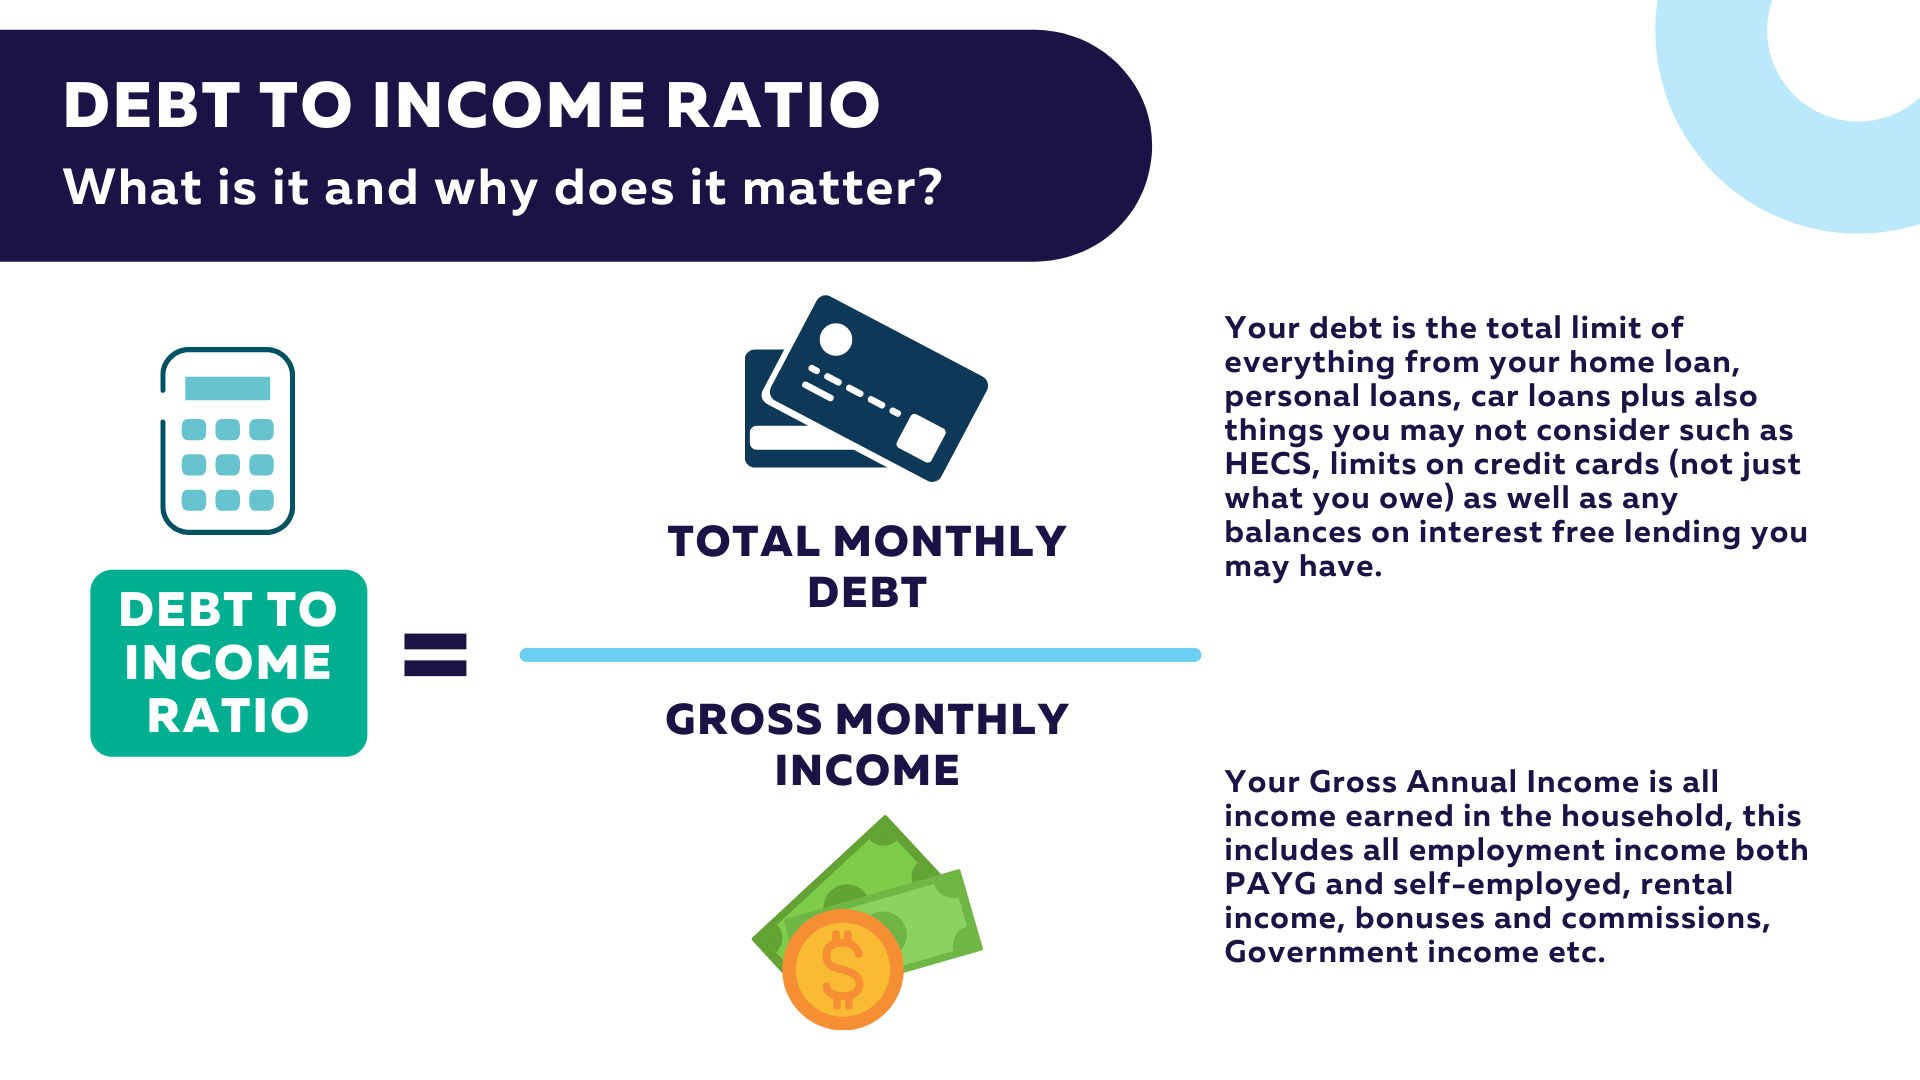
When it comes to securing a loan, one of the key factors that lenders consider is your Debt-to-Income (DTI) ratio. This ratio is a measure of your monthly debt payments relative to your gross monthly income. Lenders use this metric to assess your ability to manage additional debt responsibly. Generally, a lower DTI ratio is more favorable as it indicates that you have more disposable income after meeting your financial obligations.
Lenders typically prefer borrowers with DTI ratios below 36%, including housing expenses, and will often offer better terms and interest rates to those individuals. On the other hand, a higher DTI ratio signals that you may be stretched thin financially and could be at higher risk of defaulting on a loan.
If you find yourself with a high DTI ratio and are looking to improve your financial situation, one effective strategy is to explore side hustles or additional income streams. Whether it’s freelancing, starting an online business, renting out property, or taking on part-time work, increasing your income can help lower your DTI ratio by boosting your overall earnings.
By showcasing these creative ways to address high DTI through supplemental sources of income on Personal Finance websites, readers can gain valuable insights and practical tips for managing their finances more effectively. Taking proactive steps towards improving their financial health can not only reduce their DTI ratio but also open up opportunities for achieving their long-term goals and aspirations.