Mastering the Art of Amortization: Key Concepts for Financial Success
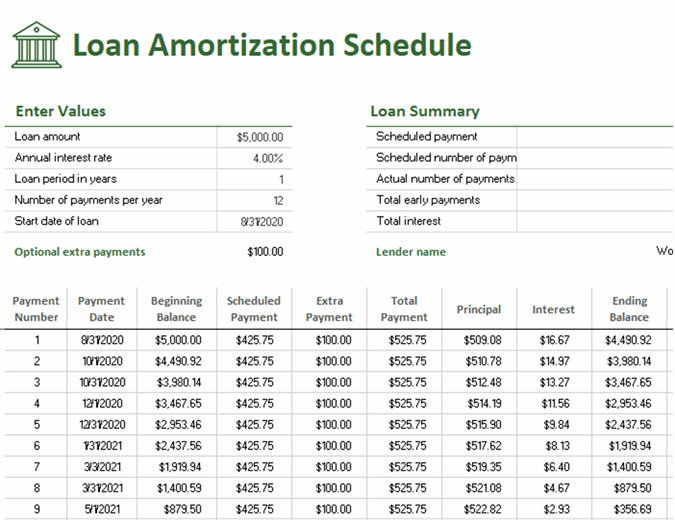
Amortization is a financial term that refers to the spreading out of payments over time for a loan or an asset. There are various types and methods of amortization used in different financial contexts. Here, we will provide an overview of key concepts related to amortization.
Accelerated amortization is a method where larger payments are made early on in the loan term, reducing the overall interest paid over the life of the loan. This can help borrowers save money and pay off their debt faster.
On the other hand, negative amortization occurs when a borrower’s payments are not enough to cover the interest due, leading to an increase in the total amount owed over time. Borrowers should be cautious about loans with negative amortization features as they can result in higher debt levels.
Amortization recapture is relevant when selling assets that have been depreciated or amortized for tax purposes. It involves recognizing previously deducted amounts as income upon sale.
Amortization schedules outline how payments are allocated towards principal and interest over time. Variations in these schedules can affect how quickly a loan is paid off and how much total interest is paid.
In commercial real estate, amortization plays a crucial role in determining loan terms and repayment structures. Lenders consider factors such as property value, cash flow projections, and market conditions when setting up amortization schedules for commercial properties.
Bi-weekly amortization involves making half of your monthly mortgage payment every two weeks instead of one full payment each month. This results in an extra payment each year and can shorten the loan term significantly.
The tax implications of amortization vary depending on whether it’s applied to tangible assets like property or intangible assets like patents. Businesses need to understand how different types of amortization impact their taxable income.
The straight-line method evenly spreads out the cost of an asset over its useful life, while the declining balance method front-loads expenses by charging more depreciation early on. The effective interest method calculates interest based on the carrying amount of a liability.
When dealing with irregular payments or balloon payments, borrowers must carefully manage their finances to ensure they can meet payment obligations at specific intervals throughout the loan term.
Prepaid expenses like insurance premiums or rent can be expensed through amortization over their respective coverage periods.
Software development costs may be capitalized as intangible assets and then expensed through systematic amortization once they are put into use.
Leasehold improvements refer to enhancements made by tenants to rented spaces; these costs can be recovered through gradual amortization.
Capitalized interest adds borrowing costs to an asset’s value during construction projects; this impacts future depreciation amounts.
Deferred financing costs incurred during obtaining loans should be recognized as assets then expensed using appropriate methods like straight-line or effective interest rate methods.
Residual value estimates what an asset could fetch at disposal; this influences depreciation calculations during its useful life span.
Overall, understanding various aspects of
amortizatio helps individuals make informed financial decisions regarding loans,
assets management taxation strategies among others