Mastering Mortgage Amortization: The Key to Financial Planning Success
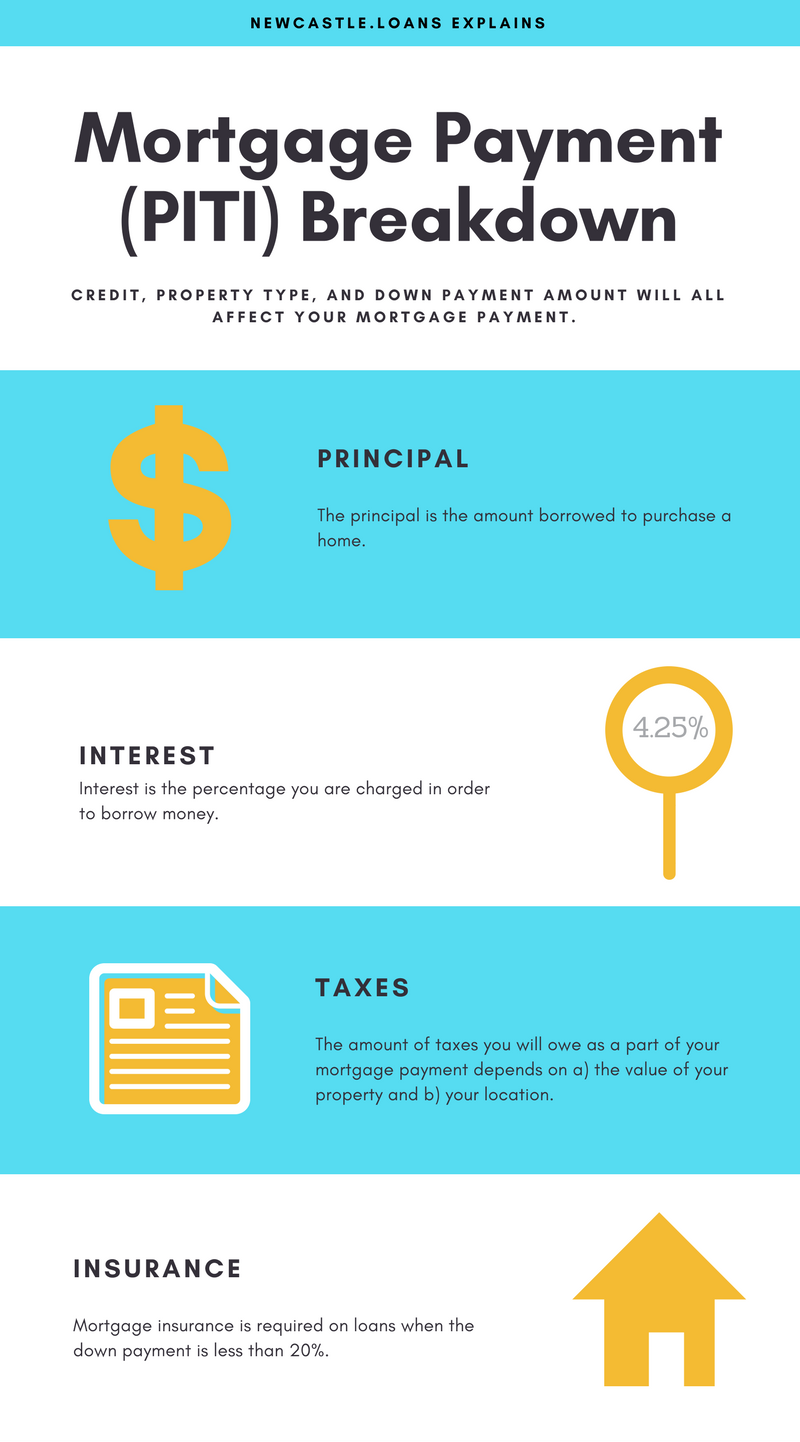
When it comes to taking out a mortgage, understanding how your payments are structured can make a significant difference in your financial planning. Mortgage amortization schedules play a crucial role in determining the breakdown of each payment you make towards your loan. In this post, we will delve into what exactly mortgage amortization schedules are, how they work, and why they are important for homeowners.
What is a Mortgage Amortization Schedule?
A mortgage amortization schedule is a table that details how each periodic payment made towards your mortgage is allocated between principal and interest over the life of the loan. It outlines precisely how much of each payment goes towards reducing the outstanding balance (principal) and how much goes towards paying the accrued interest.
How Does a Mortgage Amortization Schedule Work?
When you first take out a mortgage, most of your initial payments go mainly toward paying off the interest on the loan rather than reducing the principal balance. This happens because lenders calculate interest based on the remaining loan amount at any given time.
As you progress through making regular monthly payments, more of each subsequent payment gets applied to reducing the principal amount owed. This gradual shift occurs because as you pay down more of the principal balance, there is less outstanding debt for lenders to charge interest on.
Why Are Mortgage Amortization Schedules Important?
1. **Understanding Payment Breakdown:** By consulting your mortgage amortization schedule, you can see exactly where each dollar of your monthly payment goes – whether it’s towards reducing debt or covering interest costs. This transparency can help you plan ahead and budget effectively.
2. **Building Equity:** As more of your monthly payments go toward paying off the principal balance, you build equity in your home faster. Equity represents ownership in your property – essentially how much of it you truly own outright.
3. **Interest Savings:** By understanding how an amortization schedule works and potentially making extra payments towards the principal when possible, homeowners can save significantly on interest costs over time by shortening their repayment period.
4. **Refinancing Considerations:** Having insight into your mortgage amortization schedule can also be beneficial if considering refinancing options or selling your home before completing the original loan term. It allows you to assess where you stand financially and evaluate potential savings or costs associated with these decisions.
5. **Financial Planning Tool:** A mortgage amortization schedule serves as a valuable tool for long-term financial planning as it shows exactly when debts will be paid off under current terms and helps forecast future cash flow requirements accurately.
In conclusion, understanding mortgage amortization schedules empowers borrowers to make informed decisions about their home loans by providing clarity on payment structure and helping them manage their finances better over time.