Navigating the Pros and Cons of Joint Accounts for Couples
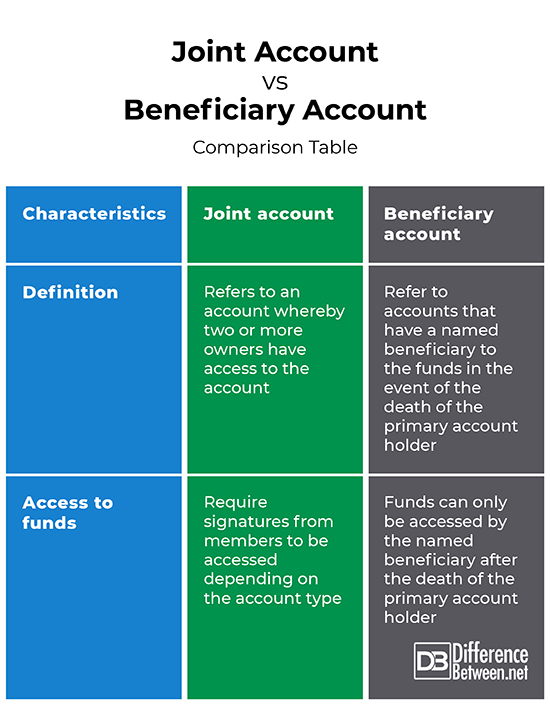
Joint accounts can be a convenient way for couples to manage their finances together. However, like any financial arrangement, there are pros and cons to consider before opening a joint account. One of the main benefits of having a joint account is that it allows both parties easy access to shared funds for expenses like bills, groceries, and other necessities. It can also promote transparency and communication about money matters in the relationship.
On the flip side, one major con of joint accounts is that each party has equal ownership and control over the funds deposited into the account. This means that both individuals have the ability to withdraw or spend money without needing permission from the other person. If trust issues arise or if one partner mismanages funds, it can lead to conflicts within the relationship.
To open a joint account, both partners typically need to visit a bank or credit union together and provide identification documents such as driver’s licenses and social security numbers. Some financial institutions may require proof of address as well. Once all necessary information is submitted, the account will be set up with both names listed as primary holders.
Managing finances in a joint account involves clear communication about spending habits, budgeting goals, and financial responsibilities. Setting financial goals as a couple can help guide decision-making when it comes to saving and spending money from the joint account. Whether it’s saving for a vacation or planning for retirement, having shared objectives can strengthen your financial partnership.
Budgeting with a joint account requires cooperation from both parties to track expenses accurately. Creating a monthly budget outlining fixed costs (like rent/mortgage payments) versus variable expenses (such as dining out) can help prevent overspending. Regularly reviewing your budget together allows for adjustments based on changing circumstances or unexpected costs.
Communication is key when discussing money matters in any relationship. Tips for effective communication about finances include scheduling regular check-ins about your joint account balance and expenditures, being honest about individual financial concerns or constraints, maintaining respect during discussions even if disagreements arise, and seeking professional guidance if needed.
Disagreements over joint finances are common among couples but handling them constructively is crucial for maintaining harmony in the relationship. Strategies like compromising on spending decisions by considering each other’s priorities or seeking mediation from a financial advisor can help resolve conflicts amicably without damaging trust.
Some couples may prefer separate accounts instead of pooling their resources into a single joint account due to personal preferences or past experiences with managing money independently. While separate accounts offer autonomy over individual finances, they may require additional coordination when it comes to shared expenses such as rent or utilities.
Safeguarding your joint account from fraud involves monitoring transactions regularly online or through bank statements, setting up alerts for unusual activity like large withdrawals or purchases outside normal spending patterns; protecting login credentials by using strong passwords; never sharing sensitive information via email/text messages; updating contact details promptly if you change addresses/phone numbers; reporting suspicious activities immediately to your bank.
Planning for the future with a joint account involves discussing long-term goals like buying property together, starting a family business venture/taking extended vacations abroad – determining how much should be saved/invested towards these aspirations jointly from income streams/savings accrued overtime while factoring individual contributions/expenses incurred along this journey ensuring equitable distribution/division upon reaching milestones/reaching milestones mutually agreed upon beforehand.