Navigating the Tax Terrain: Understanding Mutual Fund Tax Implications
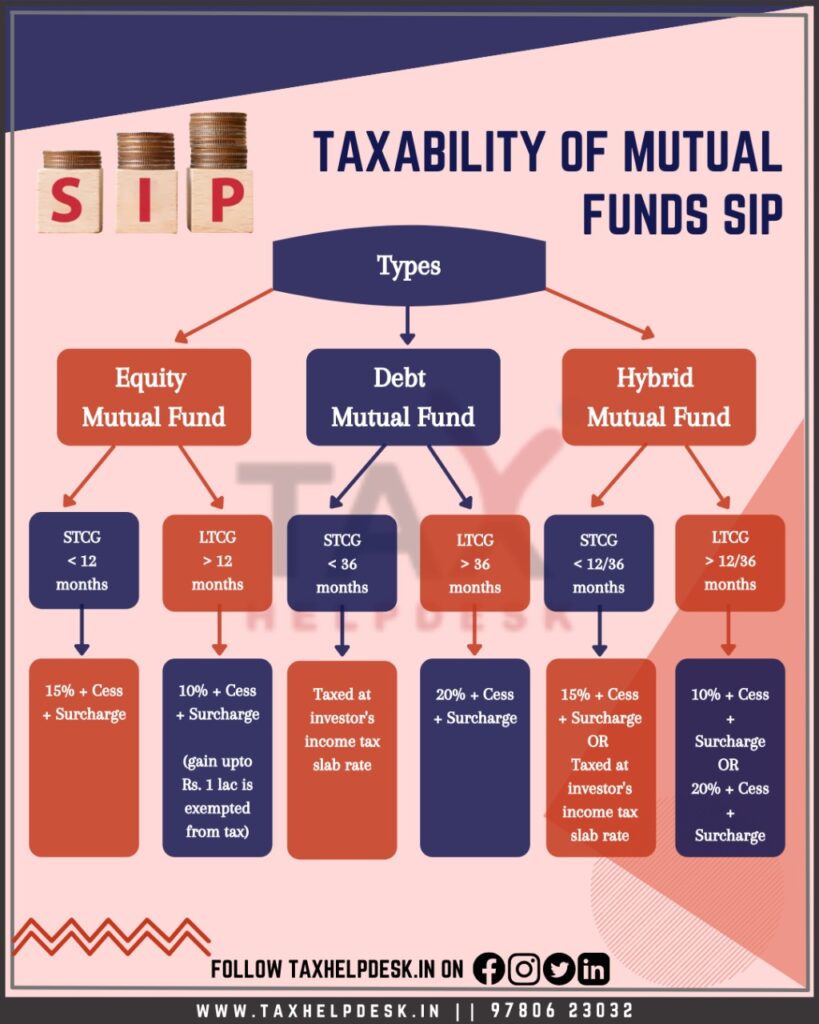
When it comes to investing, mutual funds are a popular option for many individuals looking to grow their wealth. Mutual funds pool money from multiple investors to invest in a diversified portfolio of stocks, bonds, or other securities managed by professional fund managers. While investing in mutual funds can be an effective way to build long-term wealth, it’s important for investors to understand the tax implications associated with these investments.
In this comprehensive guide, we will delve into the various tax considerations that investors need to keep in mind when investing in mutual funds.
### Types of Mutual Funds
Before delving into the tax implications of investing in mutual funds, it’s essential to understand the different types of mutual funds available:
1. **Equity Funds**: These funds primarily invest in stocks and carry higher volatility but offer potential for high returns.
2. **Bond Funds**: Bond funds invest in fixed-income securities such as government or corporate bonds and are generally considered less risky than equity funds.
3. **Money Market Funds**: These funds invest in short-term debt securities like Treasury bills and provide lower returns but are relatively low-risk.
4. **Index Funds**: Index funds aim to replicate the performance of a specific market index like the S&P 500 and typically have lower expense ratios compared to actively managed funds.
### Tax Implications
#### Capital Gains Tax
One of the key tax considerations when investing in mutual funds is capital gains tax. When you sell your mutual fund shares at a profit, you will incur a capital gain that is subject to taxation. Capital gains can be categorized as either short-term (held for one year or less) or long-term (held for more than one year).
– **Short-Term Capital Gains**: Short-term capital gains are taxed at ordinary income tax rates, which can range from 10% to 37% depending on your income level.
– **Long-Term Capital Gains**: Long-term capital gains are generally taxed at lower rates ranging from 0% to 20%, again depending on your income bracket.
It’s important for investors to consider their holding period when selling mutual fund shares as it can significantly impact their tax liability.
#### Dividend Income
Mutual fund investors may receive dividend income from their investments. Dividends can either be qualified or non-qualified based on how long the underlying securities have been held by the fund before distribution.
– **Qualified Dividends**: Qualified dividends are taxed at long-term capital gains rates, which are typically lower than ordinary income tax rates.
– **Non-Qualified Dividends**: Non-qualified dividends are taxed at ordinary income tax rates similar to interest income.
Investors should pay attention to how dividends received from mutual funds are classified for tax purposes as it can affect their overall tax liability.
#### Distribution Taxes
Mutual funds distribute realized capital gains and dividend income among shareholders periodically throughout the year. It’s crucial for investors who hold these funds in taxable accounts to be aware of potential distribution taxes they may face even if they haven’t sold any shares themselves.
These distributions could lead to taxable events regardless of whether an investor has benefited directly from them through share sales. Investors should carefully review distribution schedules provided by mutual fund companies and plan accordingly for any resulting taxes owed.
#### Tax-Efficient Investing Strategies
To mitigate the impact of taxes on investment returns, there are several strategies that investors can employ:
1. **Tax-Loss Harvesting:** Selling underperforming investments at a loss can help offset capital gains taxes on profitable trades.
2. **Holding Period:** Opting for long-term investment horizons minimizes short-term capital gains taxes.
3. **Tax-Efficient Funds:** Choosing index or passively managed ETFs over actively managed mutual fnds can reduce unnecessary turnover and associated capital gains distributions.
4 .**Utilizing Retirement Accounts:** Investing in mutual funs through retirement accounts like IRAs or 401(k)s offers immediate ta advantages since contributions ar made with pre-tax dollars nd earnings grow t ax-deferred until withdrawal .
By incorporating these strategies into their investment approach , invstors an maximize after-tax returns n thir muutal und portfolios .
### Conclusion
While mutul fuds r populr vehicle fo building walth , invstors must remain vigilant bout thir t x plicatins . By understanding h w capi al g ins d vidend incom , distribu ion txes , nd employing t x-efficient i vesting trategie s uch s lax-l ss harvesting nd utilizing retirm nt ac unts , nv st rs c n mitigate h impact f axes n heir inv stm nt rtns .
It’s advisabl fr individua ls o onsult with finanial adv sor r t xpert tx pr fessional o craft personalized ax stratege i accordance w th ir unique fina cial goals nd situatio s . Throug educ tion nd dilige ce , ivestors ca navig te he complexit es f axes associ ted ith mutu l fu ds ensuring hat thy maxim ze th ir after-t x return nvestm ts .