Maximizing Dividend Income: Taxable vs. Tax-Advantaged Accounts
Dividends are a crucial component of any investment portfolio, as they offer a steady stream of income in addition to capital appreciation. When it comes to investing in dividend-paying stocks or funds, one important consideration is whether to hold them in a taxable account or a tax-advantaged account like an Individual Retirement Account (IRA) or 401(k). Each option has its own set of advantages and disadvantages that investors should carefully weigh before making a decision.
Taxable Accounts:
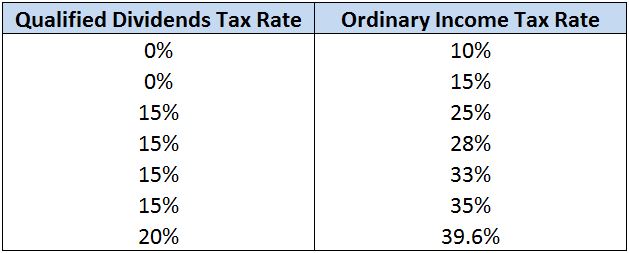
Investors who choose to hold dividend-paying investments in taxable accounts will be subject to taxes on the dividends they receive each year. Dividend income is typically taxed at the investor’s ordinary income tax rate, which can range from 10% to 37% depending on their total income for the year. Additionally, if an investor sells shares of stock that have appreciated in value, they will also be subject to capital gains taxes on any profits realized.
One advantage of holding dividend investments in a taxable account is that there are no restrictions on when investors can access their money. Unlike retirement accounts, which have penalties for early withdrawals before age 59 1/2, taxable accounts allow investors to sell assets and withdraw funds at any time without facing penalties.
Another benefit of holding dividends in a taxable account is the ability to take advantage of favorable tax treatment for qualified dividends. Qualified dividends are those paid by U.S. corporations or qualified foreign corporations that meet certain criteria set by the IRS. These dividends are taxed at long-term capital gains rates, which are generally lower than ordinary income tax rates.
However, one major drawback of holding dividend investments in a taxable account is the potential impact on overall tax liability. High-income earners may find themselves pushed into higher tax brackets due to the additional income generated by dividends, leading to higher taxes not only on their dividend income but also potentially on other sources of income as well.
Tax-Advantaged Accounts:
On the other hand, holding dividend investments in tax-advantaged accounts like IRAs or 401(k)s offers several benefits related to taxation and retirement planning. Contributions made to these accounts are often tax-deductible (for traditional IRAs and 401(k)s) or made with pre-tax dollars (for Roth IRAs), allowing investors to reduce their current-year taxable income while saving for retirement.
Additionally, earnings within these accounts grow tax-deferred until withdrawn during retirement. This means that investors do not have to pay taxes each year on dividends earned within these accounts, allowing their investments to compound over time without being eroded by annual tax liabilities.
For traditional IRAs and 401(k)s, withdrawals made during retirement are taxed as ordinary income based on the investor’s marginal tax rate at that time. Roth IRA withdrawals are generally not subject to taxes since contributions were made with after-tax dollars; however, there may be penalties for withdrawing earnings before age 59 1/2 unless certain conditions are met.
Another advantage of holding dividend investments in tax-advantaged accounts is the ability to rebalance your portfolio without triggering immediate capital gains taxes. In a taxable account, selling appreciated assets can lead
to capital gains liabilities; however,
within an IRA or 401(k), buying and selling assets does not trigger immediate taxation since all transactions occur within the sheltered confines of the account.
Furthermore,
investors who anticipate being in a lower
tax bracket during retirement than
during their working years may benefit from deferring taxation until later years when they will likely owe less in taxes overall.
Choosing Between Taxable and Tax-Advantaged Accounts:
When deciding where
to hold dividend-paying investments,
investors should consider factors such as
their current marginal tax rate,
expected future marginal
tax rate during retirement,
investment goals,
time horizon,
and liquidity needs.
Individuals nearing retirement who anticipate needing access
to funds sooner may prefer
holding some dividend-producing
assets outside
of retirement accounts
in order
to avoid restrictions on early withdrawals.
Conversely,
those with longer time horizons
may benefit from maximizing contributions
to IRAs and 401(k)s
in order
to take full advantage
of compounding growth potential
without annual taxation.
Ultimately,
the best approach
will depend
on each individual’s unique financial situation,
goals,
and risk tolerance.
It may even make sense
for some investors
to utilize both
taxable
and
tax-advantaged
accounts
in order
to diversify
their holdings
and optimize
their overall
tax efficiency.
In conclusion,
dividend-paying investments offer
an attractive source
of passive income
for investors looking
towards building wealth
over time.
The decision
of where
to hold these assets—
whether
in taxable
or
tax-advantaged
accounts—
will depend
on various factors including
current
income levels,
retirement goals,
and investment timelines.
By carefully weighing
the pros
and cons
of each option,
investors can tailor
their asset allocation strategy
accordingly
while maximizing returns
and minimizing unnecessary
tax liabilities.
Disclaimer: The information provided here is for educational purposes only──it does not constitute financial advice.
Readers should consult witha licensed financial professionalbefore making any investment decisions.