Navigating the Pros and Cons of Joint Accounts: A Guide to Shared Finances
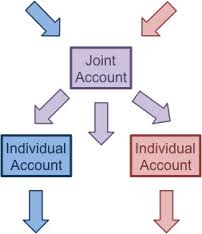
Joint accounts can be a convenient and practical way for individuals to manage shared finances, whether it’s for couples, roommates, siblings, business partners, parents and children, or any other group with financial ties. However, before deciding to open a joint account or add someone to an existing one, it’s essential to understand the pros and cons associated with joint accounts.
### Pros of Joint Accounts:
1. **Convenience**: Joint accounts allow multiple individuals to access shared funds easily for expenses like bills or common goals.
2. **Transparency**: All parties involved can see transactions in the account, promoting trust and transparency in financial matters.
3. **Shared Financial Responsibilities**: Joint accounts facilitate sharing financial burdens like rent payments or utility bills among all holders.
4. **Simplified Budgeting**: Managing shared expenses becomes more straightforward when using a joint account as everything is consolidated in one place.
5. **Emergency Preparedness**: In case of emergencies where immediate access to funds is necessary, having a joint account can provide quick solutions.
### Cons of Joint Accounts:
1. **Loss of Autonomy**: With joint accounts, each party has equal control over the funds in the account which could lead to conflicts about spending decisions.
2. **Liability Concerns**: Every party on the joint account is responsible for any debts incurred through that account; thus if one person mismanages finances or overdrafts the account, all holders are affected.
3. **Relationship Strain**: Disagreements over money management may strain relationships between individuals who share a joint account.
4. **Risk Exposure**: If one individual faces legal issues such as bankruptcy or divorce proceedings, funds in a jointly held account may be vulnerable.
5. **Privacy Concerns**: As all parties have access to transaction history in the joint account, personal spending habits might become visible leading to privacy concerns.
### Joint Account vs Individual Account:
– An individual account provides sole ownership and control over finances while a joint account allows multiple people access and authority over the same funds.
– Individual accounts are ideal for maintaining independence in managing personal finances whereas joint accounts are suitable for collaborative financial responsibilities.
### Managing Finances with Unmarried Couples/Roommates/Siblings/Business Partners:
– Communication is key when managing finances jointly; establish clear guidelines on how money will be spent/shared.
– Regularly review transactions together and set expectations regarding budgeting and saving goals.
### Closing a Joint Account:
– To close a joint bank account both parties must agree on this decision.
– Transfer remaining funds from the closed joint bank account into new individual accounts before officially closing it.
### Tax Implications of Joint Accounts:
– Interest earned on funds within a jointly held savings/checking accounts should be reported proportionally by each holder on their tax returns.
### Setting Financial Goals with A Joint Account:
1. Identify common financial objectives such as saving for vacations or purchasing assets together.
2. Determine fixed contributions from each party towards these goals regularly.
### Protecting Yourself within A Joint Account Arrangement:
1. Monitor your balance regularly
2. Set up alerts for unusual activity
3) Discuss security measures like using strong passwords
In conclusion…
Joint accounts offer benefits like convenience and shared responsibility but also come with risks such as potential conflicts and liability concerns if not managed effectively by all parties involved.