Navigating the World of Bonds: Understanding Different Types and Risks
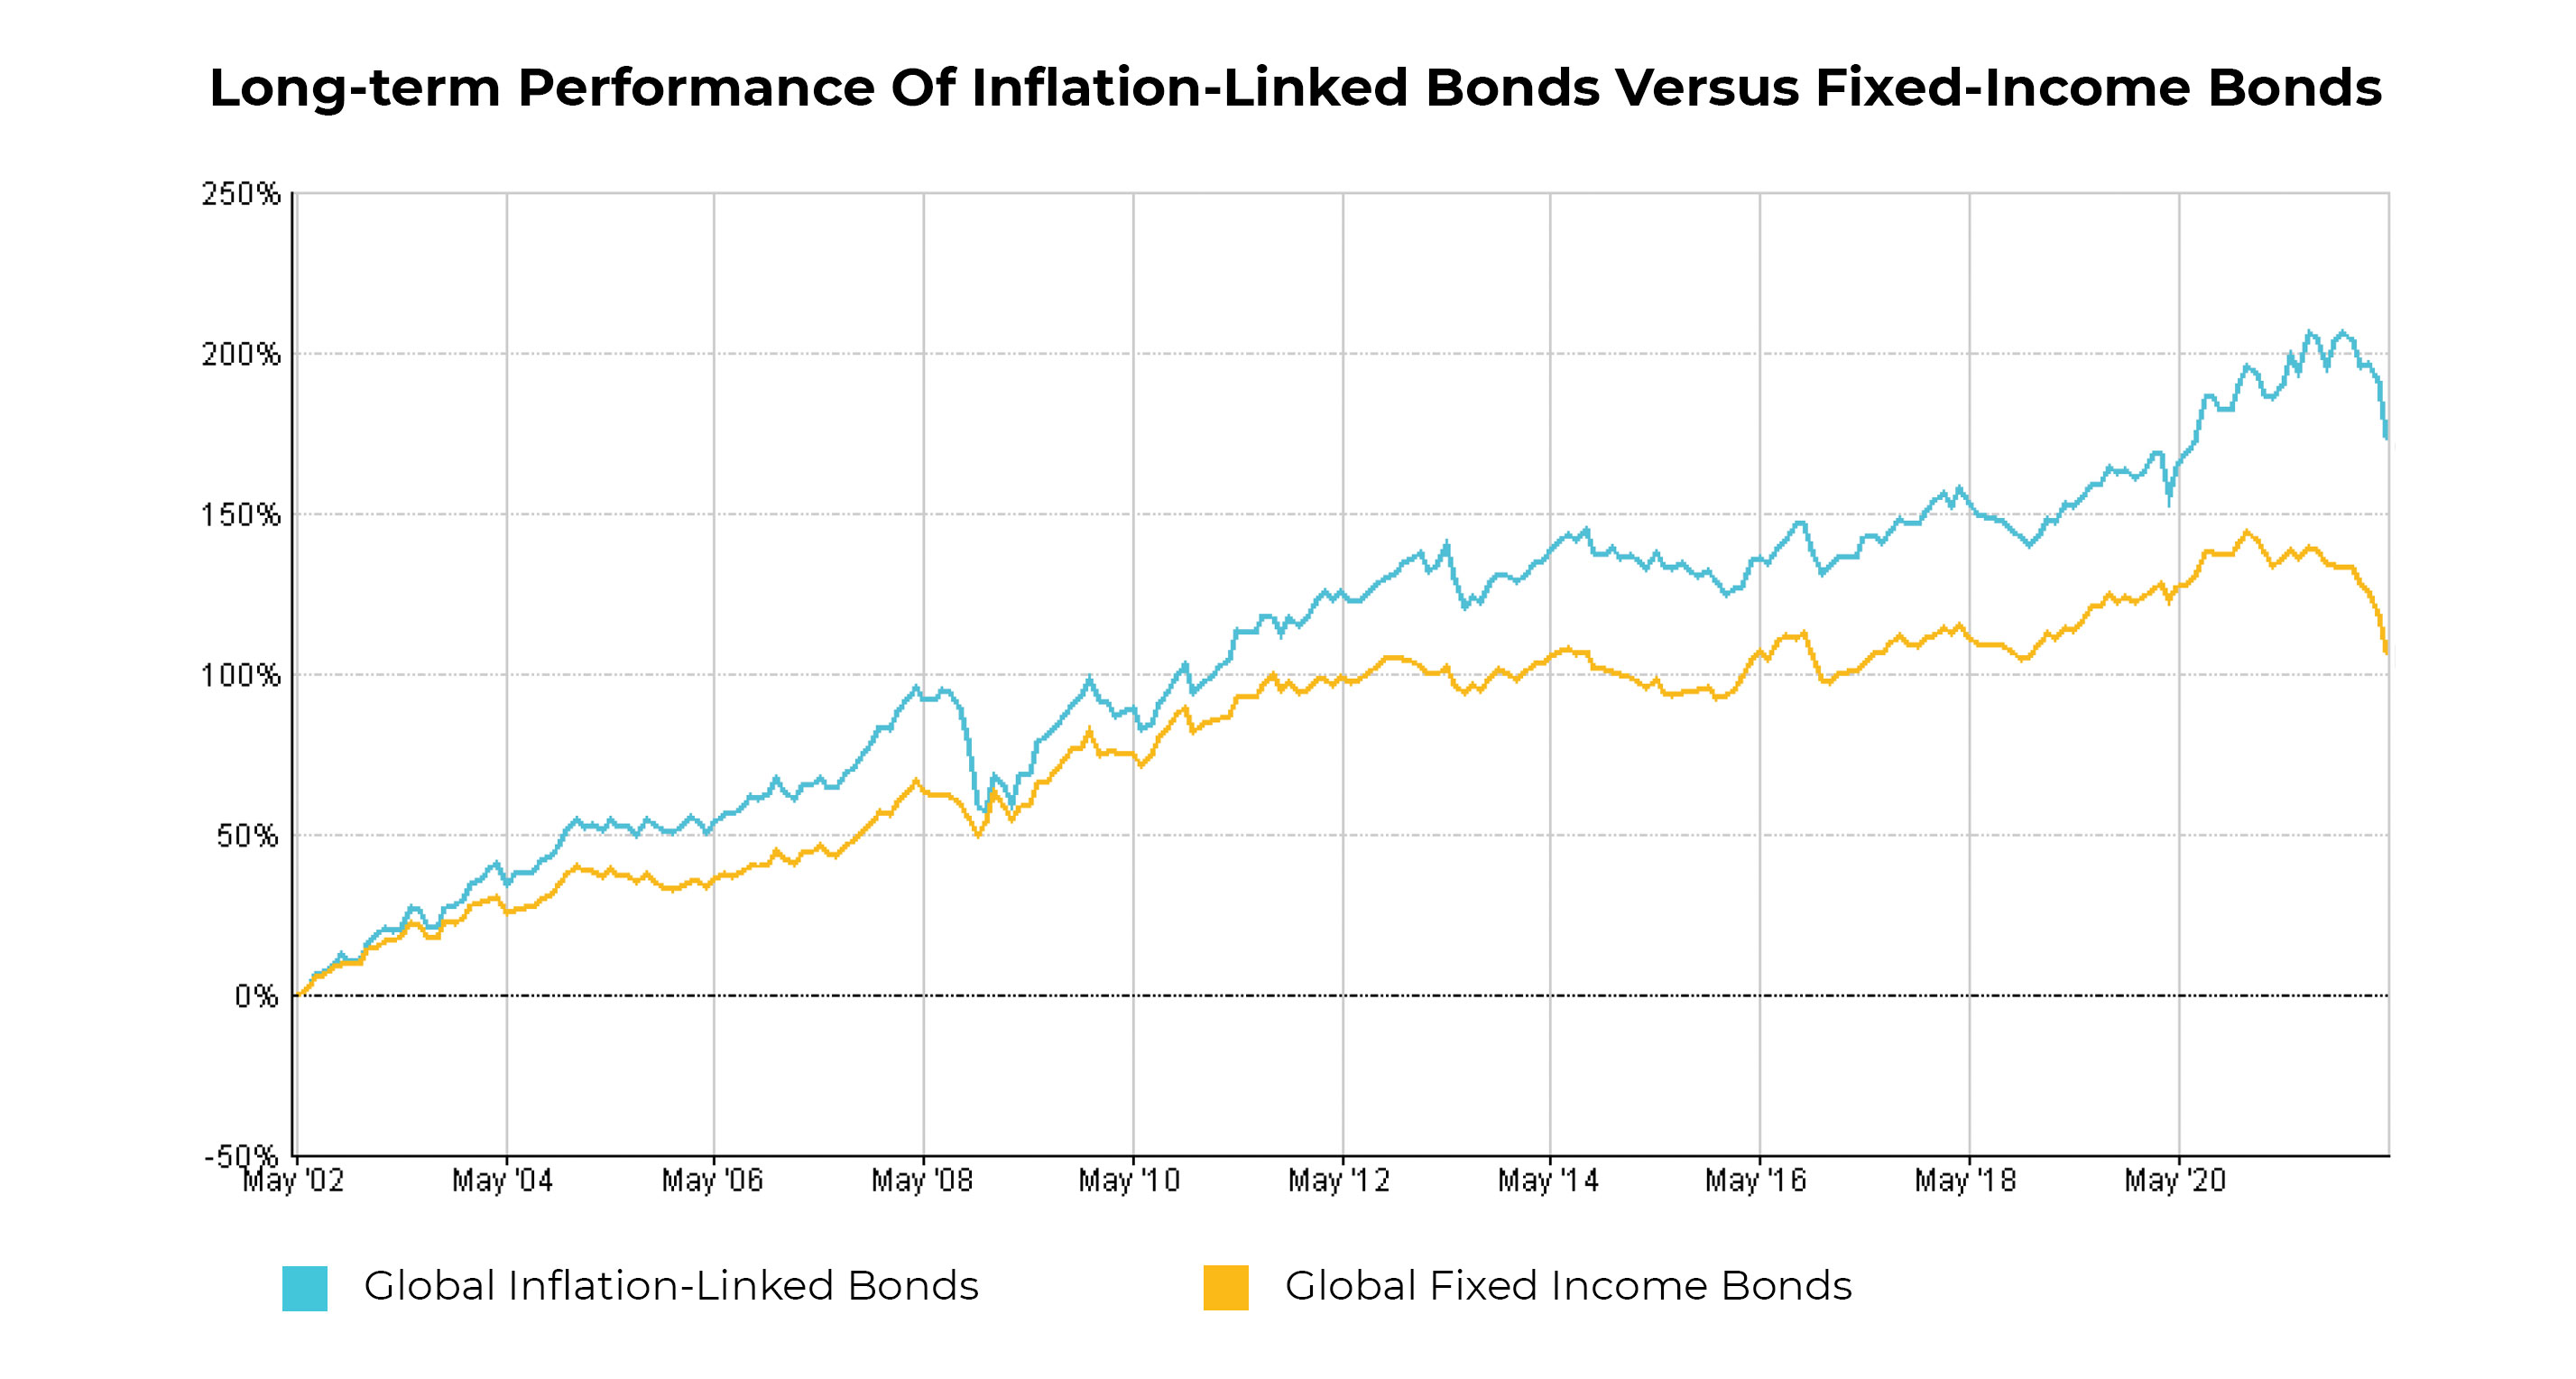
Inflation-linked bonds, also known as inflation-indexed bonds or real return bonds, are fixed-income securities whose principal value is adjusted periodically based on changes in the official inflation rate. These bonds provide investors with protection against the erosion of purchasing power caused by inflation. The most common type of inflation-linked bond is the Treasury Inflation-Protected Securities (TIPS) issued by the U.S. Department of the Treasury. TIPS offer a guaranteed real rate of return above inflation, making them an attractive investment for those seeking to hedge against rising prices.
Callable bonds are debt securities that give the issuer the right to redeem or “call” the bonds before their maturity date. This feature provides flexibility to issuers by allowing them to refinance at lower interest rates if market conditions become favorable. However, callable bonds may pose a risk to investors as they could face reinvestment risk if their bond is called away and they have to reinvest their funds at lower prevailing interest rates.
Credit spread risk refers to the potential for the difference in yield between a corporate bond and a benchmark government bond of similar maturity to widen due to changing perceptions of credit quality or market conditions. An increase in credit spreads can lead to a decline in bond prices, particularly for lower-rated or high-yield bonds. Investors in corporate bonds should carefully assess credit spread risk and diversify their portfolios accordingly.
Asset-backed securities (ABS) are financial instruments backed by pools of assets such as mortgages, auto loans, or credit card receivables. These securities allow originators like banks and financial institutions to transfer risks associated with these assets while creating new investment opportunities for investors. ABS can be structured into different tranches with varying levels of risk and return profiles, appealing to a wide range of investors with different risk appetites.
Collateralized loan obligations (CLOs) are specialized ABS that consist of pools of leveraged loans made to corporations with below-investment-grade credit ratings. CLOs are divided into tranches based on seniority, with each tranche offering different levels of risk and return potential. While CLOs can provide attractive yields compared to traditional fixed-income investments, they also carry higher default risks due to their exposure to non-investment-grade borrowers.
Convertible bonds are hybrid securities that combine features of both debt and equity instruments. These bonds allow holders the option to convert their bond holdings into shares of the issuing company’s stock at predetermined terms and conditions. Convertible bonds provide investors with potential capital appreciation through equity participation while offering downside protection through fixed income payments.
Floating rate notes (FRNs) are debt instruments whose interest payments fluctuate based on changes in short-term interest rates or reference benchmarks such as LIBOR (London Interbank Offered Rate). FRNs offer investors protection against rising interest rates compared to fixed-rate securities since their coupon payments adjust periodically according to prevailing market conditions.
Mortgage-backed securities (MBS) represent an ownership stake in a pool of residential mortgage loans bundled together by issuers such as government-sponsored enterprises (GSEs) like Fannie Mae and Freddie Mac or private financial institutions. MBS enable investors to gain exposure to mortgage-related cash flows without directly owning individual home loans while providing liquidity for mortgage lenders.
Stripped Treasury securities are created by separating the interest payments from principal repayments on U.S. Treasury Bonds or Notes into distinct securities known as STRIPS (Separate Trading Of Registered Interest And Principal Securities). By stripping these components apart, investors can customize their exposure either solely towards receiving periodic interest income or focusing on realizing capital gains upon maturity without worrying about reinvestment risks associated with coupons payments.
Zero-coupon bonds do not make regular interest payments like traditional fixed-income securities but instead sell at a discount from face value and pay out only at maturity when they redeem for par value representing accrued compound interest over time until final repayment date arrives Zero-coupon-bonds offers deep discounts upfront but lack ongoing cash flow; thus suitable for long-term goals where income isn’t necessary immediately yet desire price appreciation over full term length
Sovereign Bonds issued by national governments typically considered low-risk investments due backing full faith taxation powers respective countries Issuers vary widely credibility stability political climate economic performance Sovereign Debt rated agencies help determine level perceived default probability sovereign nations
Municipal Bonds issued state local governments agencies finance public projects infrastructure facilities Municipalities issue general obligation GO revenue-backed types GO backed taxes budgetary appropriations revenue fees charges specific projects Revenue-backed rely project-specific revenues toll roads airports municipal utilities Education healthcare essential services Green energy environmental purposes increasingly popular green sustainable initiatives Catastrophe disaster recovery invest rebuilding communities affected natural disasters earthquakes hurricanes floods wildfires Perpetual Consols governments companies perpetual consols perpetuities pay periodic coupon forever without requiring repayment principal initial issuance akin form equity Step-up start relatively low-interest rates gradually increase predetermined intervals remainder life security protect investor future increases expected returns Inverse Floaters structured products adjustable-rate tied benchmark index resets opposite direction Index moves up inverse floater coupon declines vice versa Extendible Notes extendible notes extend maturity dates beyond original expiration periods benefit increasing uncertainty economic environment Range Accrual Notes
Combination floating-rate note range accrual option pays coupons determined whether reference index remains within specified range certain observation dates If index stays inside bounds investor receives enhanced payout If breaches thresholds standard floating rate applies thereby limiting downside personal finance website readers likely encounter various types mentioned article educational purposes understand characteristics risks benefits particular instrument align overall investment objectives Risk tolerance timeframe factors consider choosing appropriate mix portfolio diversification key mitigating impacts one asset class underperformance another Always consult professional financial advisor guidance personalized advice tailored individual needs circumstances