Decoding the Debt-to-Income Ratio: Your Key to Financial Health
Debt-to-Income Ratio: A Key Metric in Financial Health
In the realm of personal finance, understanding and managing your debt-to-income ratio (DTI) is crucial for maintaining a healthy financial standing. The DTI is a metric used by lenders to assess an individual’s ability to manage monthly payments and repay debts. It provides valuable insights into how much of your income goes towards paying off debt, which directly impacts your financial stability and creditworthiness.
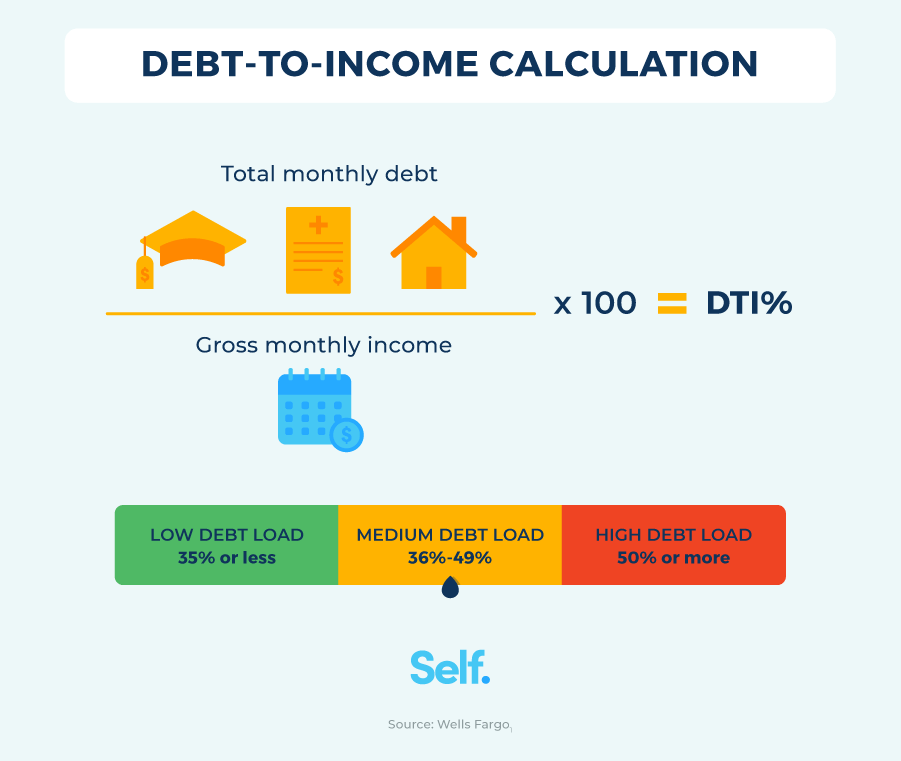
Calculating your DTI is relatively simple. Start by totaling all your monthly debt payments – including mortgage or rent, car loans, student loans, credit card minimum payments, and any other outstanding debts. Then divide this sum by your gross monthly income (before taxes). Multiply the result by 100 to get a percentage, which represents your DTI.
The ideal DTI ratio varies depending on the lender and type of loan but generally falls within the range of 36% or lower. This means that no more than 36% of your gross monthly income should go towards debt repayment.
Your DTI plays a significant role in determining your credit score. A high DTI indicates that you are using a large portion of your income to service debts, signaling potential financial strain. Lenders view high DTIs as risky since it may be challenging for individuals with high ratios to meet their financial obligations promptly.
To improve your DTI ratio, consider strategies such as increasing income through side hustles or negotiating higher pay at work, reducing expenses where possible, and consolidating debts to potentially lower interest rates and streamline payments.
Debt consolidation can help simplify finances by combining multiple debts into a single loan with a lower interest rate. While this can positively impact your DTI by reducing overall monthly payments, it’s essential to avoid accumulating new debts after consolidation to prevent further financial strain.
Common mistakes when calculating DTI include forgetting certain debts like subscription services or underestimating variable expenses. It’s crucial to account for all recurring liabilities accurately to obtain a true reflection of your financial situation.
Lenders use the DTI ratio as part of the loan approval process to gauge an individual’s capacity to take on additional debt responsibly. A lower DTI typically signals good financial health and increases the likelihood of loan approval at favorable terms.
Balancing debt repayment with other financial goals is vital for long-term wealth building. While reducing debt is important, allocating funds towards savings for emergencies or retirement ensures you have a safety net in place during unforeseen circumstances without relying on additional borrowing.
Managing a high DTI involves prioritizing debt repayment, exploring options like refinancing for better terms if applicable, and adjusting spending habits to free up more funds for savings or extra loan repayments.
Changes in income directly affect the DTI ratio – higher earnings decrease the percentage going towards debt while reduced income may increase it. Regularly reviewing and updating your budget helps track these fluctuations and adjust spending accordingly.
Understanding front-end (housing expenses only) versus back-end (total recurring monthly debts) ratios provides insight into different aspects of one’s finances – especially relevant when applying for mortgages where specific thresholds must be met based on these ratios.
For mortgage approval, lenders typically look for front-end ratios below 28% and back-end ratios under 36%. These benchmarks ensure borrowers can comfortably afford their home loans without being overly burdened by other debts.
When considering student loans or auto financing, aim for lower percentages than general guidelines due to these being specific types of debt that should ideally comprise smaller portions of total income compared to housing costs.
Interest rates significantly influence the affordability of loans; higher rates lead to larger portions going towards interest rather than principal repayments – subsequently impacting one’s overall
DTIDeveloping solid budgeting tools aids in monitoring and improving one’s DtD Ithrough tracking expenses efficiently setting realistic targets evaluating progress over time
Two popular methods fo rreducing DTDare snowballavalanche methodSnowballinvolves paying off smallest debtfirsstimmediately moving onto nextAvalanche tackling highestinterest firstsave money long termBotheffec tive depending preference level risk tolerance
Emergency funds pivotal maintaining healhty TIDIunexpected expensesariseEnsuring enoughsavings coverthree six months living expensesshields reliancecredit cardsoradditional borrowing times crisisNegotiating creditorslowermonthly payment amountspossible especially facing temporaryfinancial hardshipExplaining situatio nshowcasing commitment repayingdebtsco uld result leniency adjustedterm srepayment
Overallawareness management DTDimpact financia lhealthcredibilitylende rsCritical understan dingimplement best practicesmaintain optimal ratiowhile working towardspersonalfinancial goals