Navigating the Complex World of Investment Taxation: Key Rules and Strategies to Know
Wash sales occur when an investor sells a security at a loss and repurchases the same or substantially identical security within 30 days before or after the sale. As per IRS regulations, any losses from wash sales cannot be deducted on your tax return but instead are added to the cost basis of the repurchased securities.
Netting rules allow investors to offset gains and losses in their investment portfolio for tax purposes. This means that if you have both gains and losses during the year, you can subtract your total losses from your total gains to determine your net capital gain or loss for tax purposes.
Capital loss carryovers refer to the ability to carry over excess capital losses from one year to offset capital gains in future years. If your capital losses exceed your capital gains in a given year, you can use up to $3,000 of those excess losses ($1,500 if married filing separately) to offset other income such as wages or salary. Any remaining unused capital losses can be carried forward indefinitely until they are fully utilized.
Short-term losses are incurred on investments held for one year or less while long-term losses apply to investments held for more than one year. Short-term losses are taxed at ordinary income tax rates while long-term losses benefit from lower tax rates.
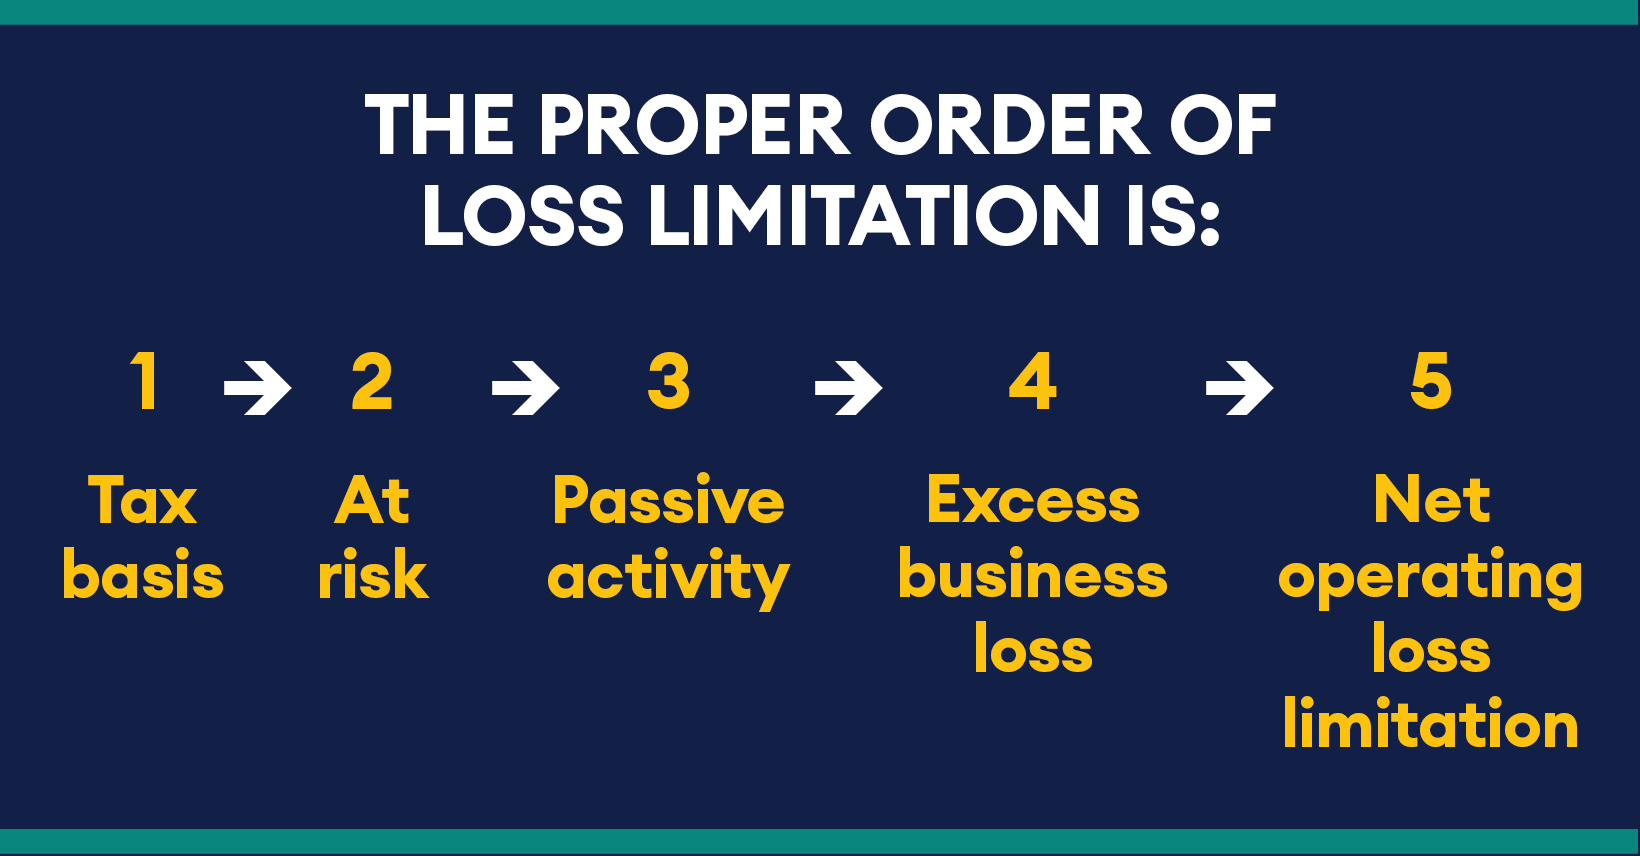
At-risk rules limit the amount of deductible loss that an individual can claim based on how much money they have invested in a particular venture. These rules aim to prevent taxpayers from deducting more than they actually have at risk in an investment.
Constructive sales rules come into play when an investor enters into certain transactions that trigger recognition of gain without actually closing out their position. The IRS treats these transactions as if there was a sale triggering potential taxes on unrealized gains.
Straddles and options trading involve complex strategies where investors may hold offsetting positions with different maturities or strike prices. Tax treatment for these strategies is intricate and requires careful consideration by investors and their tax advisors.
Worthless securities refer to investments that have become completely worthless due to bankruptcy or insolvency of the issuing company. Investors can claim a deduction for these securities as a capital loss on their tax return.
Section 1244 stock allows individuals who invest in small business corporations to deduct up to $100,000 (or $200,000 if married filing jointly) of ordinary business losses against other income rather than being subject only to capital loss limitations.
Passive activity limitations restrict the extent to which passive activity losses (losses from rental properties or businesses where you do not materially participate) can be used against active income like wages, salaries, and portfolio income.
Capital loss limitations for individuals cap annual deductions against ordinary income at $3,000 ($1,500 if married filing separately). However, any unused portion can be carried forward indefinitely until fully utilized
Trusts and estates also face restrictions on claiming capital loss deductions with similar limitations as individuals but with additional complexities due to their unique structures
For married couples filing separately each spouse is limited individually under applicable limits; they cannot combine their respective limits when reporting separate returns
Losses on personal property are generally not deductible unless it’s used for business purposes whereas collectibles may qualify but subject special limitations
Losses related small business investments might qualify under Section 1244 stock provisions
Real estate investments typically give rise long term Capital Gains/Losses; however short term speculation could result short term Capital Gains/Losses
Foreign Investments could raise complications due varying jurisdictions; consult professionals specializing international taxation
Casualty & theft Losses need satisfy specific criteria & mustn’t covered insurance reimbursements
In conclusion managing investment related taxation involves understanding various nuances including timing holding period categorization asset type treatment jurisdictional implications among others consulting professional advice crucial optimally navigating this complex landscape