Navigating the Tax Terrain: Maximizing Mutual Fund Investments
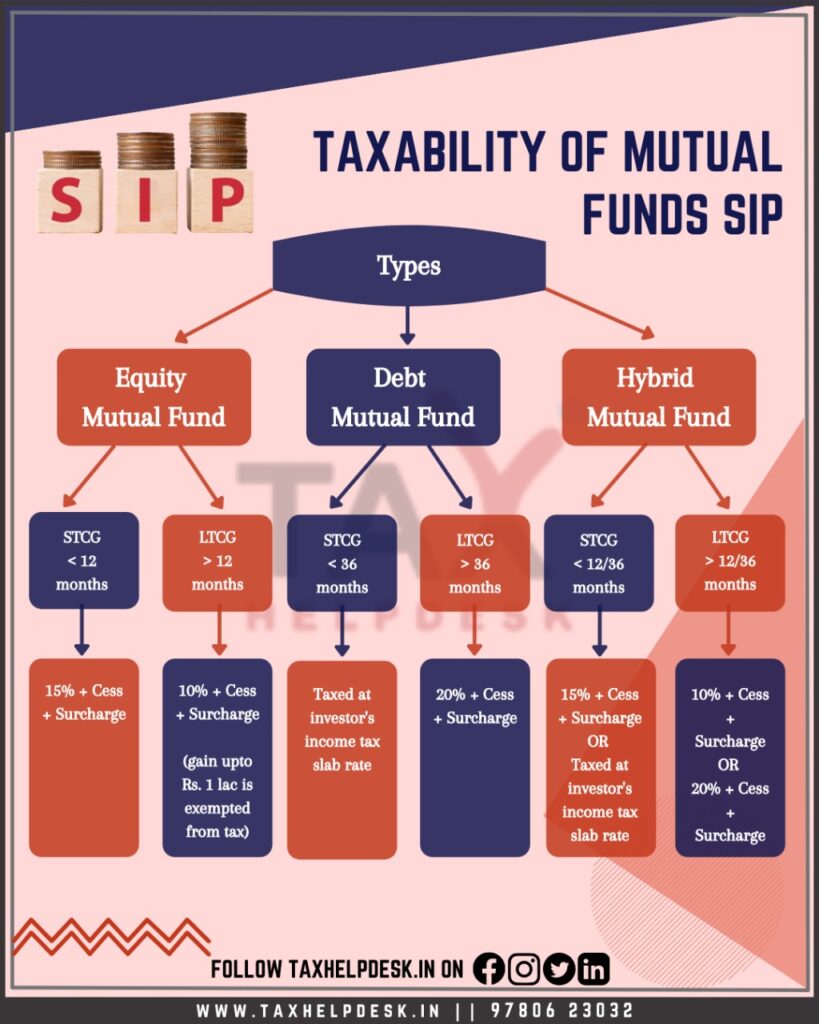
Investing in mutual funds can be a smart way to grow your wealth over time, but it’s important to understand the tax implications that come with this type of investment. Mutual funds are investment vehicles that pool money from multiple investors to purchase a diversified portfolio of stocks, bonds, or other securities managed by professional fund managers.
When it comes to taxes, there are several key considerations for investors in mutual funds:
1. Capital Gains Distributions:
One of the primary ways that investors in mutual funds may incur taxes is through capital gains distributions. When a mutual fund sells securities within its portfolio at a profit, those gains are passed on to shareholders in the form of distributions. These distributions are typically made annually and can be subject to capital gains taxes.
There are two types of capital gains distributions: short-term and long-term. Short-term capital gains occur when securities are held for one year or less before being sold at a profit, while long-term capital gains result from holding securities for more than one year before selling them.
Short-term capital gains are taxed at ordinary income tax rates, which can range from 10% to 37%, depending on your tax bracket. On the other hand, long-term capital gains are taxed at lower rates – either 0%, 15%, or 20% – based on your income level.
2. Dividend Distributions:
Mutual funds may also distribute dividends earned from the stocks or bonds held within their portfolios. These dividends can be classified as qualified or non-qualified based on how long the underlying securities have been held.
Qualified dividends are taxed at the same preferential rates as long-term capital gains – either 0%, 15%, or 20%. Non-qualified dividends, however, are taxed at ordinary income tax rates.
It’s important for investors to keep track of these dividend distributions throughout the year and ensure they report them accurately on their tax returns.
3. Capital Gains Taxes Upon Sale:
In addition to annual distributions received from mutual funds, investors will also incur capital gains taxes when they sell their fund shares for a profit. If you sell your shares after holding them for more than one year, any resulting gain will be treated as a long-term capital gain and taxed accordingly.
Conversely if you sell shares held for one year or less resulting in profits it would be considered short term and thus subjected to higher ordinary income tax rates
4.Tax Loss Harvesting
If an investor has experienced losses with some investments , they could offset these losses against any realized taxable income generated by sale off profitable assets . This is known as Tax loss harvesting strategy which could help reduce overall taxable liability .
5.Potential Tax-Efficient Alternatives :
For individuals concerned about managing their tax liabilities while investing in mutual funds , exploring low turnover index Funds might prove beneficial since these tend not generate frequent taxable events due minimal trading activities compared actively managed Funds
In conclusion , While investing in mutual funds offers diversification benefits along with access professional management expertise it’s important acknowledge potential impact associated with Tax obligations . By being aware different types Taxes applicable like Capital Gain Distributions , Dividends & realizing strategies like Tax loss harvesting available could assist optimize overall after-tax returns . It always recommended consult financial advisors CPAs prior making investment decisions taking into account individual circumstances and goals .