Decoding the Enigmatic World of Private Equity Funds: A Deep Dive into Complex Structures and High Returns
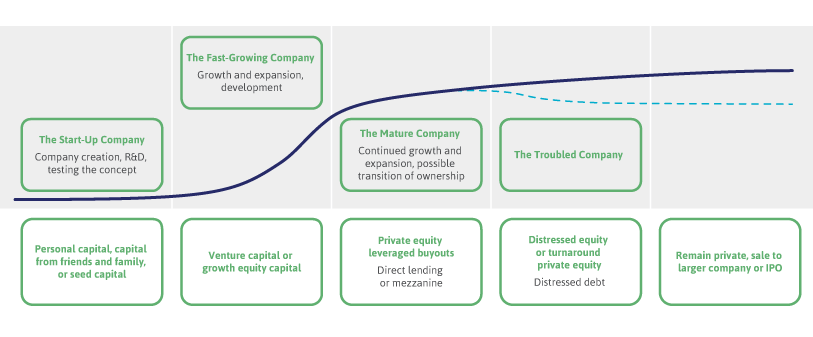
Private equity funds have long been a source of fascination, confusion, and controversy in the world of finance. These investment vehicles are known for their complex structures and high potential returns, making them both alluring and intimidating to investors.
At its core, a private equity fund is a pool of capital raised from high-net-worth individuals, institutional investors, and other sources with the goal of investing in privately held companies. The fund is typically managed by a team of professionals who make investment decisions on behalf of the investors.
One key feature of private equity funds is their closed-ended structure. Unlike mutual funds or exchange-traded funds (ETFs), which allow investors to buy and sell shares at any time, private equity funds have a limited lifespan during which capital commitments are made by investors upfront and locked in for a set period, usually around 10 years.
The lifecycle of a typical private equity fund can be divided into several stages:
1. Fundraising: In this initial stage, the general partner (GP) – the entity responsible for managing the fund – raises capital from limited partners (LPs) through fundraising efforts. LPs commit to investing certain amounts over the life of the fund.
2. Investment Period: Once the fundraising stage is complete, the GP begins deploying capital into target companies. This phase can last several years as investments are made strategically to generate returns for investors.
3. Harvesting: As portfolio companies mature and increase in value, the GP seeks opportunities to exit these investments through various means such as an initial public offering (IPO), merger or acquisition. The proceeds from these exits are distributed back to investors.
4. Liquidation: Towards the end of the fund’s term, remaining assets are sold off or liquidated to distribute final proceeds to investors before closing down the fund.
The fee structure associated with private equity funds is another notable aspect that sets them apart from traditional investment options. GPs typically charge management fees based on committed capital (usually around 1-2% annually) along with performance fees known as carried interest (typically 20% of profits above a specified threshold). This fee model aligns interests between GPs and LPs since GPs only earn significant profits when they deliver strong returns for their investors.
Despite their potential for high returns due to active management strategies like leveraged buyouts and operational improvements within portfolio companies, private equity funds also come with risks that should not be overlooked by prospective investors:
– Illiquidity: Investments in private equity funds are illiquid compared to publicly traded securities since there is no secondary market where shares can be easily bought or sold.
– High Minimum Investments: Private equity funds often require substantial minimum investments that may exclude smaller retail investors.
– Lack of Transparency: Due to regulatory exemptions enjoyed by private markets participants, information disclosure requirements are lower than those imposed on public companies.
Nevertheless ,private equity remains an attractive asset class for many sophisticated investors seeking diversification beyond traditional stocks and bonds .By understanding how these funds operate ,investors can make informed decisions about whether allocating capital towards them aligns with their financial goals .