Maximize Tax Savings: High-Income Earners Benefit from Capital Loss Deductions
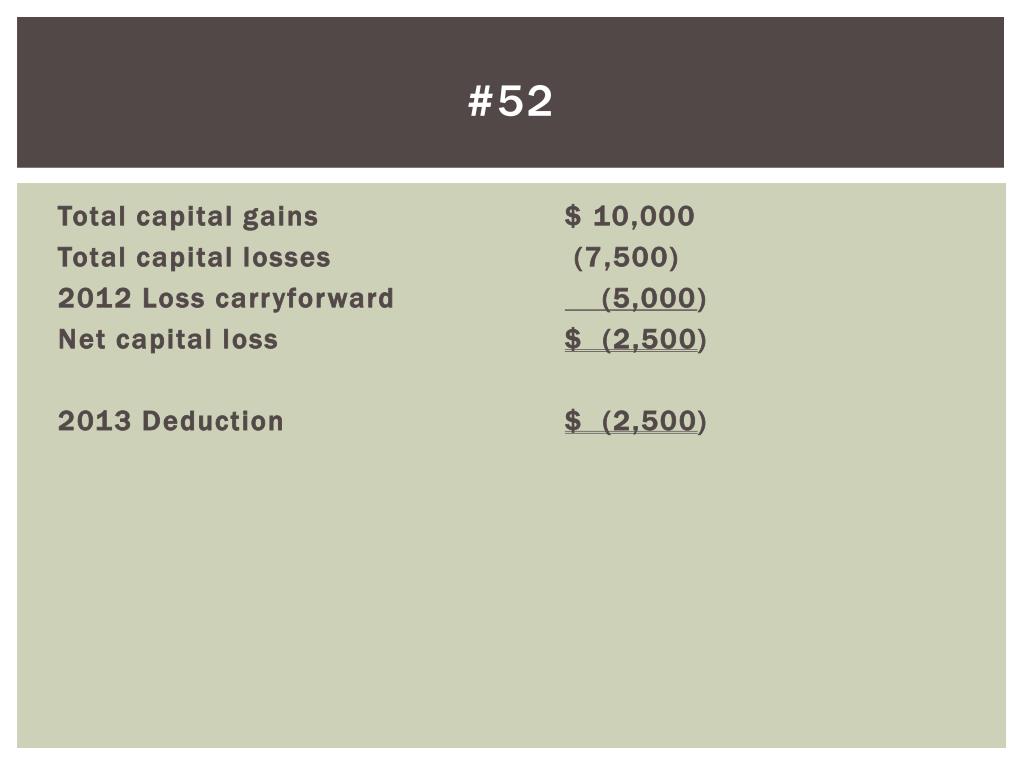
Capital loss deductions can be a valuable tax-saving strategy for high-income earners looking to offset their capital gains and reduce their overall tax liability. When an investment, such as stocks, real estate, or other assets, is sold for less than its original purchase price, it results in a capital loss. These losses can be used to offset capital gains realized in the same tax year or carried forward to future years.
For high-income earners who are subject to higher tax rates on their capital gains, utilizing capital loss deductions can help lower their taxable income and potentially move them into a lower tax bracket. This can result in significant savings come tax time.
It’s important for high-income earners to understand the rules and limitations surrounding capital loss deductions. The IRS allows individuals to deduct up to $3,000 of net capital losses ($1,500 if married filing separately) against ordinary income each year. Any excess losses beyond this amount can be carried forward indefinitely to offset future capital gains.
Additionally, there are specific rules regarding the timing of when capital losses can be claimed and how they can be applied against different types of income. It’s crucial for high-income earners to work with a qualified tax professional or financial advisor who understands these complexities and can help optimize their tax strategy.
Overall, taking advantage of capital loss deductions is a smart way for high-income earners to minimize their tax burden and maximize their wealth-building potential. By carefully managing investments and leveraging these deductions effectively, individuals can keep more of their hard-earned money working for them in the long run.