Maximize Your Money: The Ultimate Guide to Effective Tax Planning
Tax planning is a crucial aspect of personal finance that can help individuals and businesses optimize their financial situation by minimizing the amount of taxes they owe. Effective tax planning involves analyzing your financial situation, understanding relevant tax laws and regulations, and implementing strategies to reduce your tax liability legally.
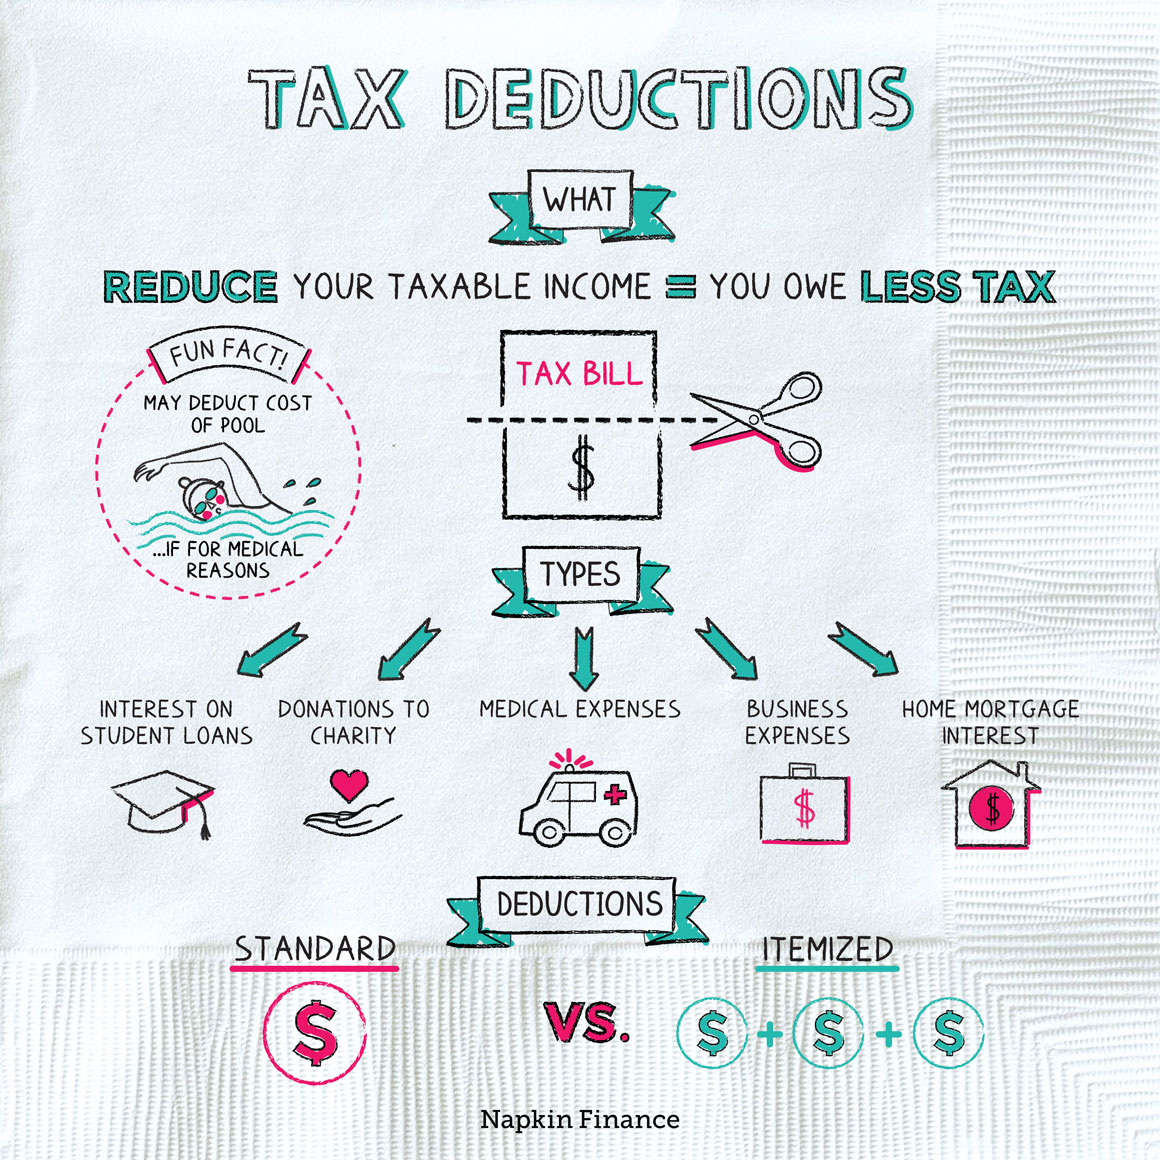
One key strategy in tax planning is taking advantage of available deductions and credits. Deductions lower the amount of income that is subject to taxation, while credits directly reduce the amount of taxes owed. Common deductions include those for mortgage interest, charitable donations, medical expenses, and education expenses. Credits such as the Earned Income Tax Credit (EITC) or Child Tax Credit can also significantly lower your tax bill.
Another important aspect of tax planning is managing your investments efficiently to minimize taxes on investment income. For example, holding investments for more than one year before selling them can qualify you for lower long-term capital gains tax rates. Additionally, investing in retirement accounts like 401(k)s or IRAs allows you to defer taxes on investment gains until you withdraw funds in retirement when you may be in a lower tax bracket.
Furthermore, it’s essential to consider the timing of income and expenses to optimize your tax situation. By strategically timing when you receive income or incur deductible expenses, you may be able to shift taxable income between different years to take advantage of lower tax rates or maximize deductions.
For business owners and self-employed individuals, there are additional opportunities for tax planning through business deductions and structuring their business in a tax-efficient manner. Properly categorizing expenses related to your business activities can help reduce taxable income while staying compliant with IRS regulations. Choosing the right entity structure for your business, such as an S Corporation or Limited Liability Company (LLC), can also have significant implications for how much you pay in taxes.
Finally, seeking professional advice from a qualified accountant or tax advisor is crucial for effective tax planning. A knowledgeable professional can help you navigate complex tax laws, identify opportunities for savings that may not be obvious to non-experts, and ensure compliance with all legal requirements.
In conclusion, proactive tax planning is an essential component of sound financial management that can lead to significant savings over time. By understanding relevant deductions and credits, managing investments wisely, optimizing the timing of income and expenses, leveraging business deductions effectively if applicable,and seeking professional guidance when needed,you can create a comprehensivetax planthathelpsyoukeepmoreofyourhard-earnedincomeandbuildabetterfinancialfuture.