Navigating Capital Gains Tax: Maximizing Benefits, Minimizing Liabilities
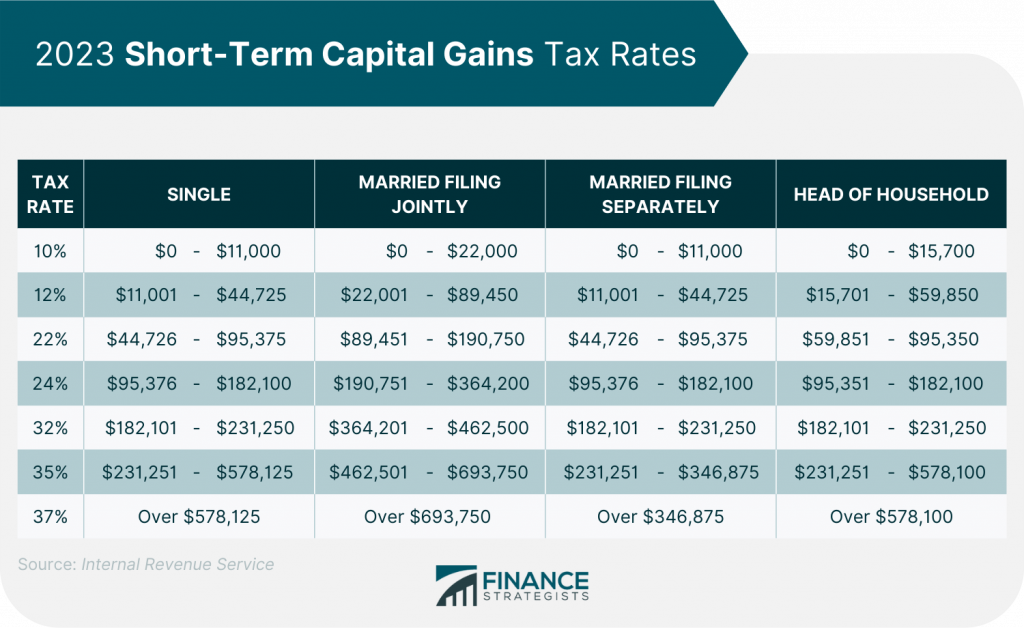
Capital gains tax rates refer to the taxes paid on profits earned from the sale of investments or assets such as stocks, real estate, bonds, cryptocurrency, and collectibles. These gains are categorized into two main types: short-term and long-term capital gains.
Short-term capital gains are profits made from selling an asset that has been held for one year or less. These gains are taxed at ordinary income tax rates, which can range from 10% to 37%, depending on the taxpayer’s income level.
On the other hand, long-term capital gains come from selling assets held for more than a year. The tax rates for long-term capital gains are generally lower than those for short-term gains and depend on the taxpayer’s income level. For most taxpayers, the rate is either 0%, 15%, or 20%.
Real estate investments also attract capital gains taxes when sold at a profit. Homeowners can benefit from an exemption that allows them to exclude up to $250,000 ($500,000 for married couples filing jointly) of capital gains from the sale of their primary residence if they meet certain ownership and usage criteria.
Stocks and bonds are common investment vehicles that can generate significant capital gains. Investors need to be aware of the tax implications when selling these assets and plan accordingly to minimize their tax liability.
Cryptocurrency has gained popularity in recent years as an alternative investment option. Capital gains on cryptocurrency transactions are subject to taxation similar to other investments, with rates based on whether they qualify as short-term or long-term gains.
Collectibles such as art pieces, antiques, coins, and precious metals also incur capital gains taxes upon sale. The tax rate for collectibles can be as high as 28%, so it’s essential for collectors to understand these implications when considering selling their items.
Net Investment Income Tax (NIIT) is an additional 3.8% Medicare surtax imposed on certain net investment income above specific thresholds. This tax applies to individuals with modified adjusted gross incomes over $200,000 ($250,000 for married couples filing jointly).
Tax-loss harvesting is a strategy used by investors to offset capital gains by selling losing investments in their portfolio. By doing this before year-end, investors can reduce their overall taxable income and potentially lower their tax bill.
Qualified Small Business Stock (QSBS) exclusion allows eligible taxpayers to exclude a portion of qualified small business stock sales from their taxable income under certain conditions.
Wash sale rules prevent investors from claiming a loss on a security sold if they repurchase substantially identical securities within 30 days before or after the sale date.
Inherited assets often receive a stepped-up basis valuation at the time of inheritance which helps reduce potential capital gain taxes when those assets are eventually sold by heirs.
Mutual funds may distribute capital gain distributions annually due to buying/selling activities within the fund throughout the year—a factor important for investors’ annual tax planning strategies
Reporting capital gains correctly on tax returns is crucial; failure could result in penalties or audits by taxing authorities.
Capital gain reinvestment strategies involve reinvesting profits back into new investments rather than cashing out completely—potentially deferring taxes until later dates.
Alternative Minimum Tax (AMT) applies higher minimum requirements compared with regular income calculations; however long term capitals still benefitting reduced AMT liabilities
Foreign investments might subject taxpayers dealing with international markets facing complex rules affecting how U.S residents pay foreign-capital-gain-taxes.
Employee stock options could lead employees paying cap-gains once exercised & sold—important timing decisions influencing potential savings.
Understanding these various aspects surrounding Capital Gains Tax will empower individuals towards making informed financial decisions while optimizing benefits & minimizing liabilities.