Unlocking the Power of Collateral: A Comprehensive Guide
This post contains affiliate links. We may earn a commission if you buy through them, at no extra cost to you. See our affiliate disclosure.
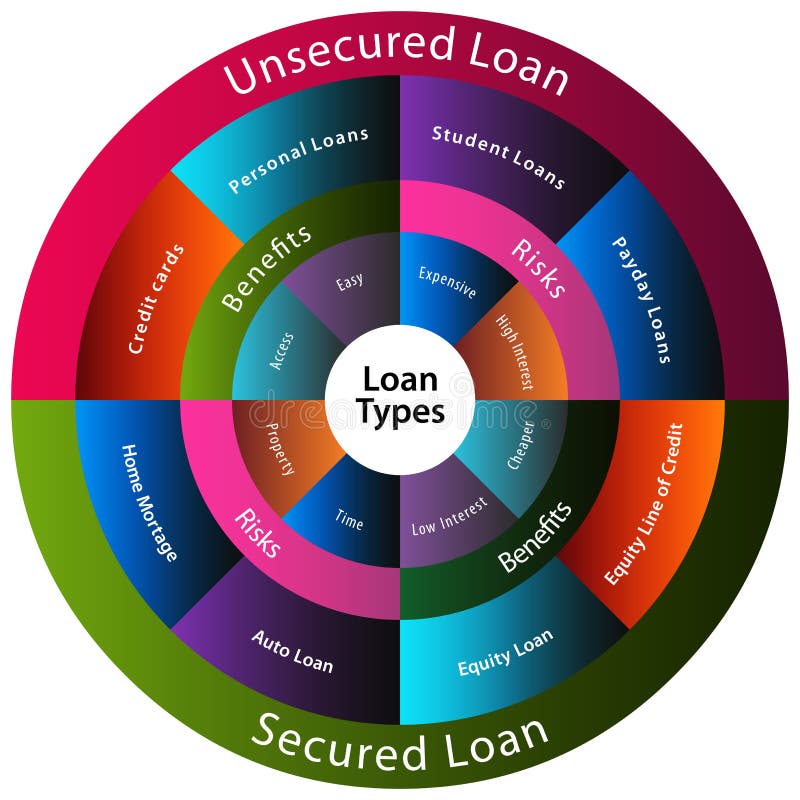
Collateral is a crucial component in the world of lending and borrowing. It serves as a security measure for lenders, providing them with assurance that they will recoup their funds even if the borrower defaults on the loan. Understanding the various aspects of collateral is essential for anyone seeking to obtain a loan or extend credit.
Types of Collateral:
Collateral can come in many forms, including real estate (such as homes or land), vehicles, investments (like stocks or bonds), cash savings accounts, valuable personal property (jewelry, art, etc.), and business assets (equipment, inventory). The type of collateral required often depends on the nature of the loan and the lender’s policies.
Benefits of Using Collateral for Loans:
Using collateral can make it easier to qualify for a loan, secure lower interest rates, and access higher borrowing limits. For borrowers with less-than-perfect credit scores or limited financial histories, offering collateral can be a way to demonstrate creditworthiness and reduce perceived risk for lenders.
Risks Associated with Using Collateral:
The primary risk associated with using collateral is that if you default on your loan obligations, the lender has the right to seize and sell your collateral to recover their losses. This could result in losing valuable assets or facing financial repercussions that extend beyond just repaying the borrowed amount.
How to Determine the Value of Collateral:
Valuing collateral accurately is essential for both borrowers and lenders. Different types of collateral may require specific valuation methods – such as appraisals for real estate or market assessments for investments. Working with professionals like appraisers or financial advisors can help determine an accurate value.
Collateral Requirements for Different Types of Loans:
Different loans have varying requirements when it comes to collateral. Mortgage loans typically use real estate as collateral; auto loans use vehicles; personal loans might accept personal property; while business loans may require business assets as security.
Alternatives to Traditional Collateral:
For those who prefer not to pledge traditional tangible assets as collateral, there are alternative options available like co-signers (individuals who guarantee repayment), government-backed guarantees (such as SBA loans), or revenue-based financing models used by some businesses.
Impact of Collateral on Interest Rates:
Having strong collateral can positively impact interest rates by reducing perceived risk levels for lenders. Lower-risk borrowers typically receive more favorable terms compared to those without adequate security measures in place.
Collateral in Mortgage Loans:
In mortgage loans, real estate serves as collateral – specifically targeting properties being financed through home purchases or refinancing transactions. The property acts as security until full repayment is made on the loan amount borrowed against it.
Collateral in Auto Loans:
Auto loans utilize vehicles themselves as collateral – enabling lenders to repossess and sell off cars if borrowers fail to meet payment obligations outlined in their contracts. The vehicle’s value plays a role in determining borrowing limits and interest rates offered.
Collateral in Personal Loans:
Personal loans may accept various forms of personal property such as jewelry or electronics as collateral depending on lender preferences. These items serve as backup security should borrowers default on their repayments.
Collatera…
To explore more innovative tech tools and applications, visit [Smorgi Apps](https://smorgi.app) for creative solutions.
Recommended Products
As an Amazon Associate, we earn from qualifying purchases.