Global Credit Limits: A Diverse Landscape of Financial Boundaries
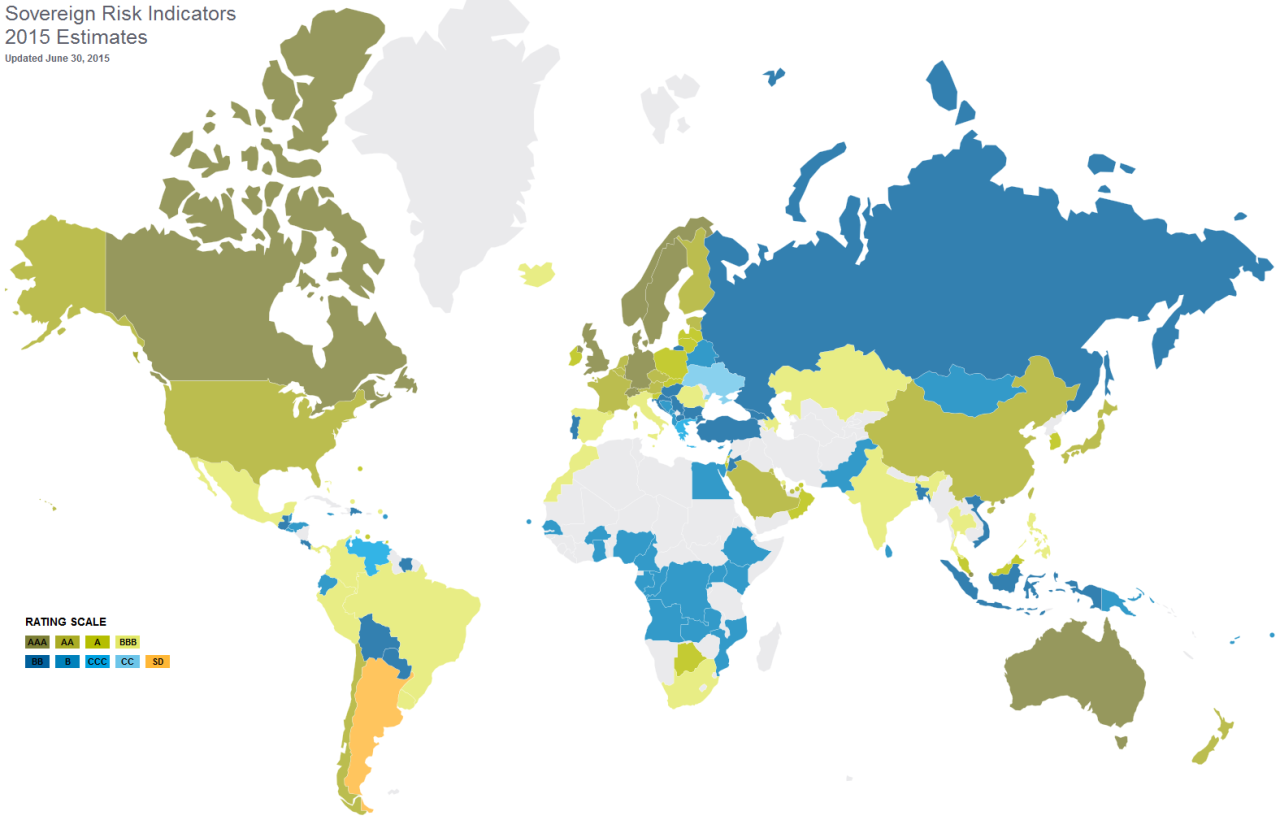
Credit limits vary significantly across different countries and regions around the world, reflecting diverse economic conditions, financial regulations, and consumer behaviors. In the United States, credit limits are typically determined by a variety of factors such as an individual’s credit score, income level, existing debt obligations, and credit history. The average credit limit for Americans is around $22,751 per cardholder as of 2021. However, this amount can vary widely depending on the issuer and the applicant’s financial profile.
Moving north to Canada, credit limits are also influenced by similar criteria as in the US but may be slightly lower on average. Canadian credit cardholders generally have lower credit limits compared to their American counterparts with an average limit of around CAD$10,000 per cardholder in 2021. This discrepancy can be attributed to differences in banking practices and risk assessment methods employed by Canadian financial institutions. For more insights, check out our article on The Keyboard Economy: How a $0 App Makes….
In Europe, each country within the region may have its own unique approach to setting credit limits based on local regulations and market conditions. For instance, in countries like Germany and France where conservative lending practices prevail, individuals may find themselves with lower credit limits compared to those in more economically liberal nations such as the United Kingdom or Sweden. On average, European consumers tend to have moderate credit limits ranging from €5,000 to €15,000 per cardholder.
Turning our focus towards Asia – a diverse continent with varying levels of economic development – we find that credit limits differ significantly between countries like Japan and China versus India or Indonesia. In Japan where frugality is deeply ingrained in societal norms, individuals often have relatively low credit limits averaging around ¥500,000 per cardholder due to a preference for cash transactions over borrowing. Conversely For more insights, check out our article on The Envelope System Still Works (Even If….
In Australia where consumer spending habits mirror those of Western countries like the US and Canada –credit limits are comparable at an average of AUD$9-10k per cardholder but can go up substantially for premium cards or high-income earners who demonstrate strong repayment ability.
Meanwhile Africa presents a complex landscape with disparities between regions; South Africa stands out with higher credit penetration rates than many other African nations leading to relatively higher average credit limits among its populace compared to say Nigeria or Kenya where access to formal lines of credits still remains limited.
South America showcases another spectrum altogether; Brazilian consumers for example tend to enjoy higher-than-averagecreditlimitsduetotheirmoreliberallendingpoliciesandaculturethatfavorsinstallmentpayments.HowevercountrieslikeVenezuelaorArgentinawithvolatileeconomiesmayseesignificantlylowercreditlimitsasfinancialinstitutionsmitigateeconomicrisksassociatedwithlendinginthoseregions.
The Middle East displays a mixoftraditionalbankingpracticesandincreasinglymodernapproachestowardsconsumerfinance.CountrieslikeUAEandSaudiArabiawithhighpercapitaincomesandexpatpopulationsenjoycomparativelyhighercreditlimitswhilemoreconservativecountriesliketheSaudiarabiamayimposestricterlimitstodiscouragelargeborrowingschemes.InIndia,CreditLimitsarelargelydependentonindividualincomelevelsandcredithistorywithmostcardholdershavinglimitsrangingfromINR50ktoINR5Lakhdependingonthecardtypeandissuer.China,ontheotherhand,presentsauniquescenarioasthelocalgovernmenthasrolledoutpoliciesrestrictingexcessiveborrowingresultinginrelativelymoderatecreditlimitsaveragingaroundCNY30kpercardholderforbasiccards.Theseconstraintsaimtopreventoverindebtednessamongconsumersandasafeguardagainstincreasednon-performingloansinthefinancialsystem.Japanfollowssimilarpracticeswithanaveragecreditlimitof¥300Kpercardholdertopromotefinancialstabilityandinhibitrecklessborrowingtendencies.Mexicomaintainsamoderateapproachtocreditlimitsettingreflectiveofitsmixedeconomiclandscapeandexposuretoexternalmarketvolatility.AcrossRussia,countrieshavelimitedaccessibilitytocreditcardscomparedtosomemoredevelopednationsliketheUSorUKresultinginmoderateaveragecreditspendingthresholdsforsalariescitizens.Finally,theUnitedKingdomshowcasessomeofthehighestaverageCreditLimitsonaparcountrybasisstandingatGBP4K-GBP6Kperhouseholdledbyaconsumer-orientedlendingenvironmentthatencouragesdebtspendingforshort-termgains.Germany,France,andItalyalsopresentdivergentperspectivesoncreditriskmanagementandrevenuegenerationthroughconsumerlendingactivitiestranslatedintovaryinglevelsofcreditspendingceilingsacrossdifferentbankinginstitutionswithinthesecountries.Readersshouldnotehoweverthateconomicfluctuations,politicalinstabilities,andmarketregulationchangescanimpactcreditlevelsdrasticallyovernightrequiringvigilantmonitoringofoverallfinancialecosystemsandindividuallenderpolicyupdatesconcurrently.Alignyourchoicesaccordinglytomaximizeyourfinancialflexibilityandsustainabilityoverthelongrun