Navigating the Maze of Depreciation: Maximizing Value and Tax Benefits
This post contains affiliate links. We may earn a commission if you buy through them, at no extra cost to you. See our affiliate disclosure.
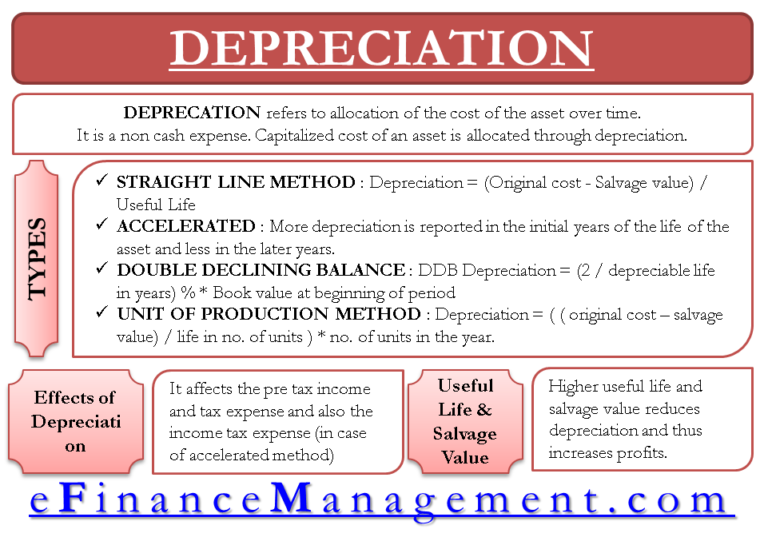
Depreciation is a fundamental concept in accounting and finance, representing the allocation of the cost of tangible assets over their useful lives. There are various methods used to calculate depreciation, each with its own set of rules and implications for businesses and individuals.
One common method is straight-line depreciation. This method evenly distributes the cost of an asset over its useful life. It is simple to calculate – you subtract the salvage value from the initial cost of the asset, then divide by the number of years in its useful life. While straightforward, this method may not accurately reflect an asset’s actual decline in value over time.
Another widely used method is the double declining balance method. This approach accelerates depreciation expenses early in an asset’s life, reflecting that many assets lose more value in their earlier years. The double declining balance method calculates annual depreciation by applying a fixed percentage (usually twice the straight-line rate) to the book value of the asset at the beginning of each year. For more insights, check out our article on The Keyboard Economy: How a $0 App Makes…. For more insights, check out our article on The Envelope System Still Works (Even If….
Units of production depreciation ties an asset’s depreciation to how much it produces or is used annually rather than time-based like other methods. This can be particularly beneficial for equipment or machinery where usage fluctuates yearly.
The Modified Accelerated Cost Recovery System (MACRS) is a tax-related depreciation method commonly used in the U.S. It assigns assets into specific classes with predetermined recovery periods based on IRS guidelines.
Component, group, and composite depreciations involve grouping assets together for ease of calculation when they have similar characteristics or are part of a larger unit.
Sum-of-the-years-digits method accelerates depreciation similar to double declining balance but uses a different formula based on an asset’s total expected years of use.
Tax-related considerations play a significant role as well; therefore, understanding tax depreciation methods such as bonus depreciation and Section 179 deduction can help businesses maximize tax benefits related to their depreciating assets.
Luxury auto limits dictate special rules for vehicles above certain values that affect how much can be depreciated annually for tax purposes. Rental properties also have specific guidelines regarding how their structures and improvements can be depreciated over time.
Listed property rules apply to business-use assets that could also be used personally – such as cars or computers – requiring stricter documentation for accurate deductions.
Qualified leasehold improvement property allows businesses leasing space to deduct associated improvement costs over shorter periods than standard commercial buildings’ useful lives.
Amortization differs from deprecation only in what type of assets it applies – intangible versus tangible ones – both aiming at spreading out costs rather than expensing them all upfront.
Impairment loss occurs when an asset loses some or all its value due to unexpected events or obsolescence before fully depreciated; this requires reevaluation and potentially adjusting financial statements accordingly.
In conclusion, mastering various types of depreciations ensures accurate financial reporting while maximizing potential tax advantages throughout an asset’s lifetime across personal finances or business operations alike.
Recommended Tools:
🎯 Get MindfulAI Keyboard to improve your experience
Many productivity enthusiasts find valuable tools and resources at [Smorgi Apps](https://smorgi.app) to optimize their daily routines.
Recommended Products
As an Amazon Associate, we earn from qualifying purchases.